Side A · Liner notes
Understanding the Impact of Synthetic Stablecoins on Financial Stability
Markets · Words by Robert Smith · Released
Synthetic stablecoins like Ethena's USDe can amplify financial shocks, leading to rapid liquidation in the crypto market. Their structural intricacies pose unique risks to financial stability.
Pablo D. Azar and Jeff Garofano
On October 10, 2025, a potential announcement of a 100 percent tariff on Chinese goods impacted multiple asset classes, including equities, Treasuries, and digital assets. This led to a significant drop in digital asset prices, a surge in trading volumes, and a notable reduction in liquidity across major exchanges. Our analysis reveals how this price shock was exacerbated by synthetic stablecoins—cryptocurrencies whose design inadvertently intensified the liquidity crisis within the digital finance environment.
Synthetic Stablecoins: A Different Structure
Synthetic stablecoins are distinct from traditional fiat-backed stablecoins, such as USDC from Circle, which are secured by reserves consisting of dollar-equivalent assets like Treasury bills and bank deposits. Synthetic stablecoins, exemplified by Ethena's USDe, use financial engineering to achieve their dollar peg. This involves combining a long position in cryptocurrencies, typically ether staked in a staking pool, with a corresponding short position in perpetual futures contracts.
Perpetual futures operate without an expiration date and are structured to follow the spot price of assets through funding rates that shift between long and short positions. If perpetual futures trade above the spot price, long investors compensate short investors; conversely, when the future trades below the spot price, shorts pay longs. This funding mechanism ensures derivatives remain closely aligned with their underlying assets, resembling the cash-futures basis trades prevalent in Treasury markets.
This relationship between assets is pivotal for the stability of synthetic stablecoins. Each issued stablecoin corresponds to a hedge position: a long position in staked ether and a short in perpetual futures. The Ethena protocol reaps the benefits from both staking rewards and any funding cost incurred from the short position. When funding rates are positive, this model is lucrative, drawing considerable investments. However, it is crucial to recognize the fragility inherent in this approach: it relies heavily on consistent liquidity in derivative markets and a stable, positive funding rate. Any significant downturn in funding conditions could lead to increased redemption pressures.
Mechanics of Minting and Unwinding at Ethena
The issuance of the USDe stablecoin highlights these mechanisms. When investors deposit ether or staked ether as collateral, Ethena’s smart contracts initiate a short position in ether perpetual futures, neutralizing price risks while ensuring income from staking and the funding rate. The rapid growth of Ethena’s total supply, which reached nearly $15 billion between early 2024 and mid-2025, is indicative of substantial collateral inflows and the allure of high yields. By August 2025, USDe ranked as the third-largest stablecoin by market capitalization.
When market conditions shift, however, this minting process can reverse. Deteriorating funding rates in ether perpetual futures reduce earnings from short positions, and increasing margin costs can diminish yield advantages. If funding rates become negative, holders of short positions must compensate long holders, which can prompt redemption activity as investors trade their USDe for ether. This process necessitates closing out the short futures in a tightening market, which requires selling ether and buying futures, creating adverse price pressures in both markets.
Illustration of Market Dynamics
Consider a scenario where an investor deposits $100,000 worth of staked ether and accesses $100,000 in synthetic stablecoins. With an annual staking yield of 3.5 percent and a positive funding rate of 10 percent, the combined return for the investor could reach approximately 13.5 percent. This occurs due to the offsetting positions: staked ether appreciates while the futures position mitigates exposure.
Conversely, if the funding rate declines to -5 percent, the dynamics reverse drastically. The investor, now facing a shortage in returns, must handle an annual net loss of 1.5 percent, inducing a wave of redemptions as others in the system replicate this behavior, leading to further price declines.
Observations from the October 10 Crisis
The events surrounding October 10 significantly illustrated the market’s fragility. A stark reduction in USDe supply can be observed through various metrics, including the shift in yield spreads between USDe and its equivalent staked assets. This period witnessed the spread turn negative—a clear sign that maintaining the futures position had become costlier than the returns from staking. Consequently, this rendered USDe unattractive, leading to mass exits from positions.
An analysis of USDe and its counterpart sUSDe reveals the mechanics behind this deleveraging episode:
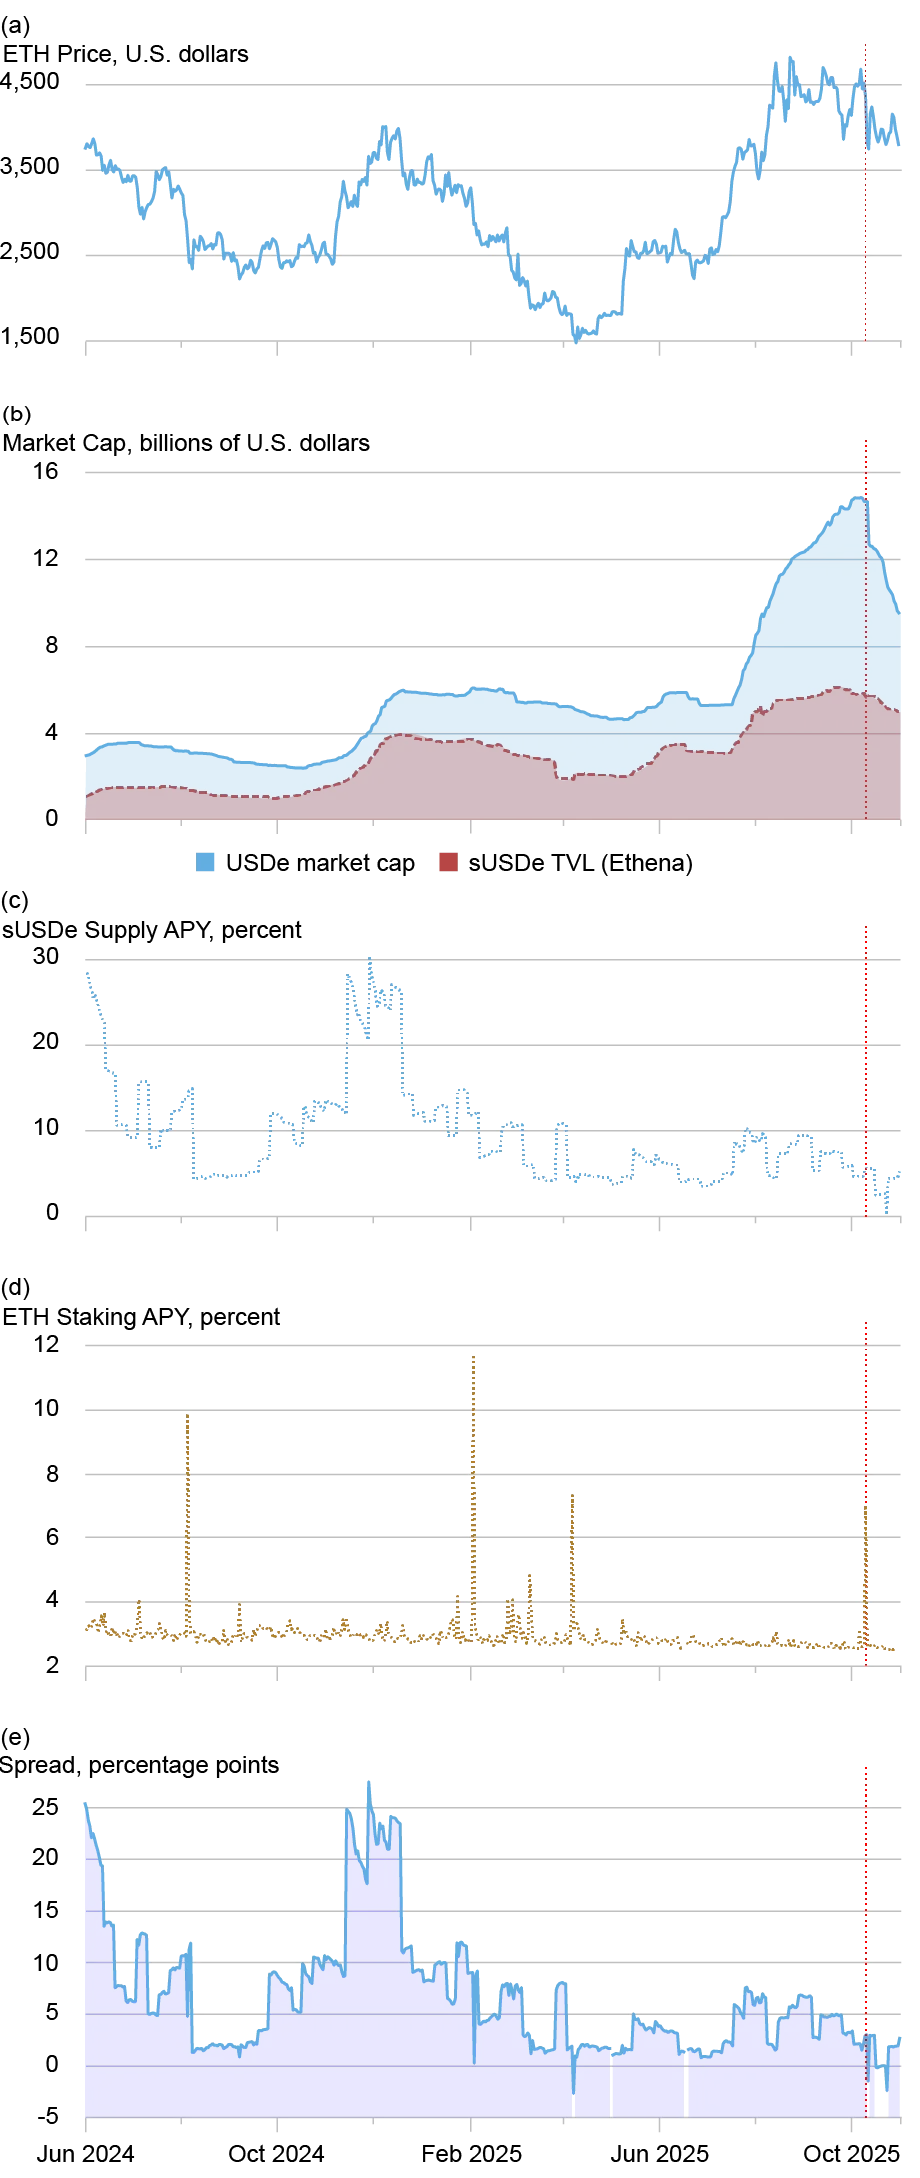
Notes: The chart illustrates the movements in ether price, market capitalization for Ethena and Staked Ethena, annual percentage yields, and the yield spread. The vertical red line marks October 10, 2025, coinciding with the tariff announcement.
The marked decline in market capitalization signifies these forced liquidations: released collateral, the closure of perpetual futures positions, and associated liquidity exits compounded the decline. This cycle emphasizes how closely tied synthetic stablecoins are to spot price movements in underlying cryptocurrencies such as ether. When yield spreads become unfavorable, redemptions pick up speed, further shrinking leveraged positions, which results in a cyclical drop in ether values.
As USDe faced an almost 13 percent contraction following this episode, marked declines drew attention to synthetic stablecoins' roles in amplifying liquidity crises. The linkage of forced selling in crypto markets with synthetic redeems exacerbated the situation, mirroring patterns observed during traditional deleveraging scenarios.
Wider Market Context and Implications
It is critical to note that the USDe deleveraging was part of a larger trend, occurring amidst systemic funding challenges across cryptocurrency and other volatile asset markets. In contrast, leading stablecoins such as Tether's USDT and Circle’s USDC effectively maintained their pegs during this episode, indicating their design robustness compared to synthetic alternatives. Notably, while Circle’s USDC saw a market capitalization decrease of $280 million, Tether’s USDT gained approximately $282 million, maintaining stability despite the surrounding turmoil.
These incidents raise essential considerations for regulators. With the increasing integration of stablecoins, tokenized money-market structures, and the expansion of digital financial products, what happens in one sector inevitably influences others. The combined market capitalization of Bitcoin, Ether, and Solana ETFs now sits around $95 billion, signaling growing interconnections between traditional finance and blockchain-based systems. The advent of tokenized treasury funds has further blurred these lines, highlighting the need for scrutiny as crises like the synthetic stablecoin unwind can transmit volatility to the broader financial landscape.

Pablo Azar is a financial research economist at the Federal Reserve Bank of New York's Research and Statistics Group.
Jeff Garofano is a capital markets trading associate at the Federal Reserve Bank of New York's Markets Group.
How to cite this post:
Pablo D. Azar and Jeff Garofano, “Synthetic Stablecoins and Financial Stability,” Federal Reserve Bank of New York Liberty Street Economics, June 23, 2026, https://doi.org/10.59576/lse.20260623
BibTeX: View |
You may also be interested in:
Disclaimer
The views expressed in this post are those of the author(s) and do not necessarily reflect the position of the Federal Reserve Bank of New York or the Federal Reserve System. Any errors or omissions are the responsibility of the author(s).


