Side A · Liner notes
Understanding the Dynamics of the U.S. Repo Market and Its Participants
Markets · Words by Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan · Released
This article delves into the intricacies of the U.S. repo market, analyzing the roles of cash lenders, dealers, and borrowers while highlighting operational differences and risks inherent in various segments.
The repo market in the United States operates as a complex framework of segments, featuring a variety of participants and differing settlement and clearing practices. To grasp this multifaceted ecosystem, it’s essential to consider why large cash lenders frequently opt for third-party agents for settlement, the necessity of central clearing in the interdealer market, and how levered investors navigate bilateral trades. This analysis will shed light on the flow of cash through repo markets, illuminating the costs and benefits that dictate the existing market structures.
What Sets Repos Apart?
At its core, a repurchase agreement (repo) involves one party selling a security, typically U.S. Treasuries, in exchange for cash with a commitment to repurchase it later—often the following business day. While similar in nature to federal funds or Eurodollar contracts, repo markets are substantially larger, with recent estimations placing the U.S. repo market's total size at over $13 trillion, compared to the approximately $200 billion daily volume in federal funds.
A defining characteristic of repos is the role of collateral. This element not only distinguishes repos from other short-term money markets but also broadens the array of participants. For example, hedge funds may utilize repos to secure particular securities, while money market funds (MMFs) view them as a tool for reducing investment risks. Consequently, the diverse set of counterparties and varied motivations stimulate customization in the execution, clearing, and settlement of repo transactions.
Participants must evaluate not just the transaction terms—such as rates, maturity, collateral type, and haircut—but also the intricate processes involved in trade verification, clearing, and the final ownership transfer of securities for cash. Each of these components carries operational, legal, and counterparty risks, leading to distinct market segments shaped by the differing approaches to managing these trade-offs.
Intermediation in Repo Markets
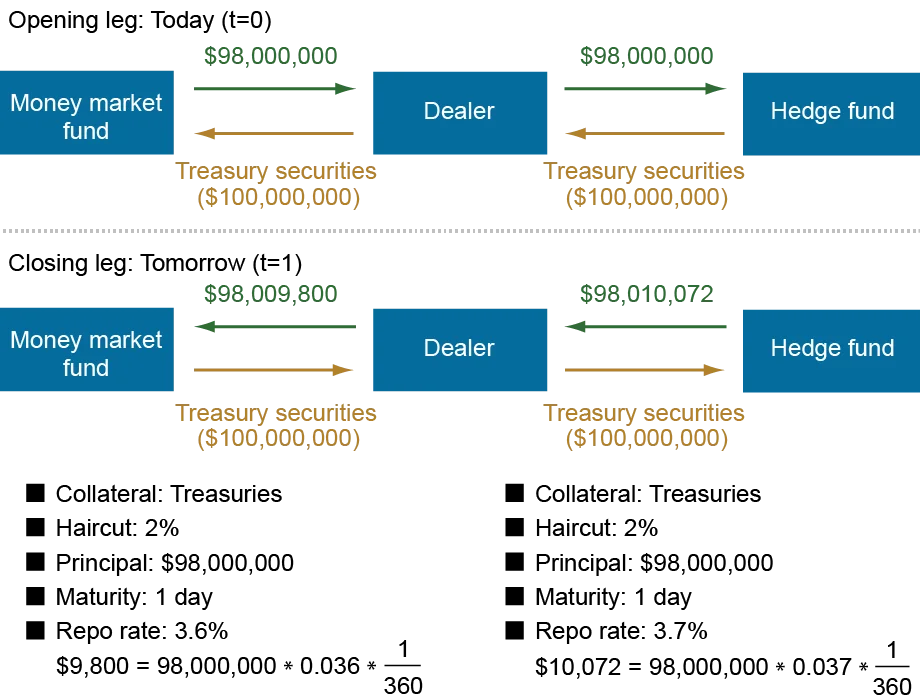
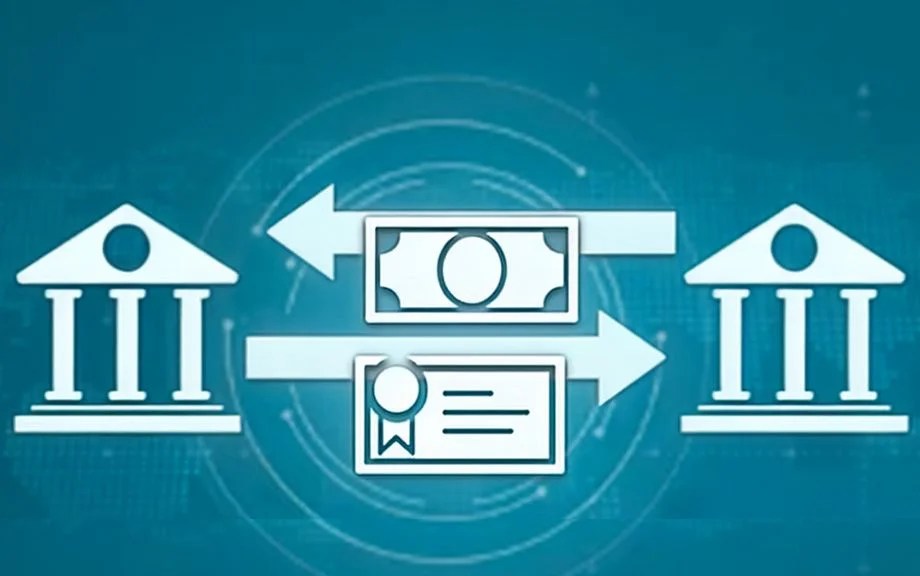
Finding appropriate counterparties in the decentralized landscape of repo markets can be challenging due to the variation among participants and their trading motives. The emergence of dealers as intermediaries has been a critical response to this challenge. Dealers act like hubs in the repo market, facilitating exchanges between ultimate borrowers and lenders by earning compensation for managing counterparty, collateral, and maturity transformation risks. For instance, a dealer might engage in a repo transaction by borrowing cash from a less risky counterparty, like a government MMF, and then lend cash via a reverse repo to a more risk-tolerant entity, like a levered hedge fund, thereby profiting from the interest rate differential.

In 2024, estimates showed that dealers were engaged in borrowing and lending substantial volumes, with a daily average of $3.7 trillion and $3.4 trillion respectively. To maintain liquidity and help manage collateral flows, dealers also transact within an interdealer market, where most trades are cleared through a central counterparty—most notably, the Fixed Income Clearing Corporation (FICC) in the U.S.). This centralized clearing system provides advantages like netting positions to reduce balance sheet costs and enhance dealer intermediation capacity. However, these benefits entail contributions to default funds and increased margining requirements.

Starting from June 2027, additional rules mandated by the SEC will require central clearing for U.S. Treasury-collateralized repos when at least one counterparty is a direct member of a registered clearing agency. This shift is likely to reframe aspects of the repo market further.
Tracing Cash Flow in Repo Markets
Cash flows into repo markets primarily via cash-rich investors, particularly MMFs seeking short-term secured investments. Dealers play a crucial role in the intermediation of these funds, channeling them to cash borrowers, such as hedge funds looking to leverage their positions. Focusing on the segments where funds flow from lenders to dealers, one observes various operational characteristics that define different market dynamics.
From Lenders to Dealers
MMFs are the primary cash lenders in the repo market. These funds utilize repos to manage client redemptions while meeting regulatory requirements dictated by SEC Rule 2a-7, which limits MMFs to high-quality, short-term debt securities. As of March 2026, government MMFs constituted over 80% of total U.S. MMF assets.
Most interactions between MMFs and dealers happen outside the centrally cleared environment, as MMFs typically prefer general collateral repos and delegate settlement functions—such as collateral valuation and management—to a third-party entity, notably the Bank of New York Mellon. This tri-party repo arrangement streamlines the settlement process without altering counterparty risk since the clearing bank acts solely as an agent.
While historical trends show that MMF lending in the centrally cleared space was minimal, a transition has been noted, with this activity nearing 40% of total MMF repo business by Q1 2026. This shift illustrates that the advantages of central clearing often outweigh the associated costs for dealers.
From Dealers to Borrowers
In the previous post in this series, it was established that repos are pivotal for hedge funds to enhance their returns. As the main cash lenders in the repo space, dealers facilitated an outstanding repo volume of $3 trillion for hedge funds by the end of Q4 2025. Unlike the lender-to-dealer transactions, the dealer-to-borrower segment primarily settles in a bilateral manner.
This bilateral structure caters to hedge funds’ need for flexibility in accessing collateral and cost efficiency, essential for transporting capital effectively. In this context, haircuts are often minimized; in fact, approximately 75% of Treasury repo trades in non-centrally cleared segments have been executed with zero haircuts. The non-centrally cleared market remains attractive to dealers, particularly where netted packages allow for balance sheet efficiencies.
Evidence of the trend toward central clearing continues as the volume of repos between hedge funds and dealers has risen, moving from 8% in early 2021 to 30% by late 2025. This activity notably peaks toward quarter-ends, emphasizing the seasonal challenges of dealer balance sheets.
Conclusion
The diverse microstructures within the U.S. repo market reflect how a heterogenous collection of participants assesses the trade-offs inherent in repo transactions. Factors influencing these distinct market segments include the costs associated with securities settlement, the preference for central clearing as a cost impulse mitigator, and innovative mechanisms like netted packages, which help manage costs in non-centrally cleared repos.
This systematic examination of the repo market illustrates not just the operational complexities involved but also the various strategies employed by participants to navigate different challenges, making it clear that understanding cash flows in this domain is crucial for stakeholders at all levels.


