Side A · Liner notes
Understanding the Central Bank's Use of Repos in Liquidity Management
Markets · Words by Gara Afonso, Jun-Davinci Choi, Gonzalo Cisternas, and Will Riordan · Released
Central banks utilize repos and reverse repos as essential tools for managing liquidity and implementing monetary policy, impacting the broader financial system.
Repos, or repurchase agreements, play a crucial role in the monetary policy framework utilized by central banks worldwide. This report explores the mechanisms by which central banks, particularly the U.S. Federal Reserve, deploy these tools to manage liquidity within financial markets.
Defining Central Bank Repos
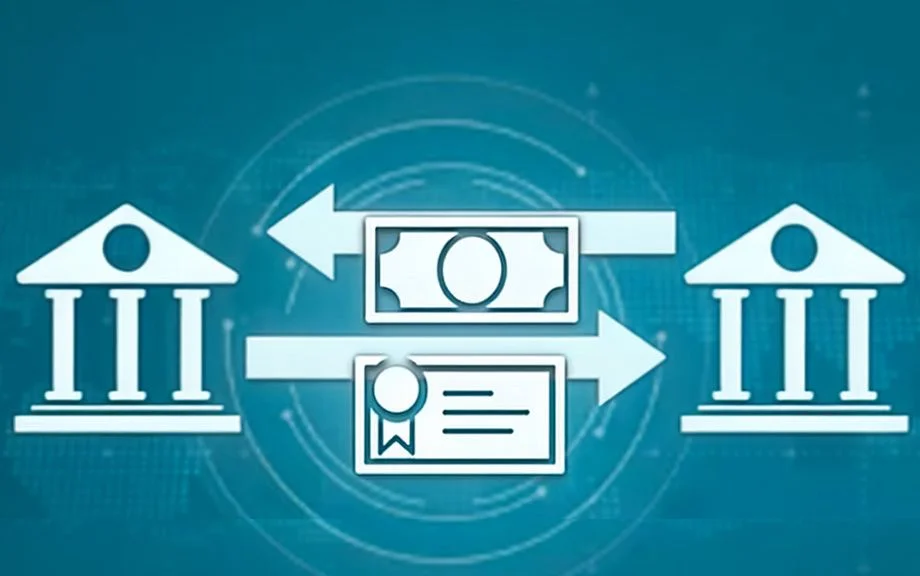
Central banks engage in repo transactions primarily to execute monetary policy and ensure the proper functioning of financial markets. Unlike private repo transactions, where a borrower sells securities to access cash, central banks operate through reverse repos when they provide cash in exchange for securities. When the Federal Reserve brokers a transaction in which it provides cash for securities, it is performing a reverse repo, demonstrating a different perspective from commercial entities.
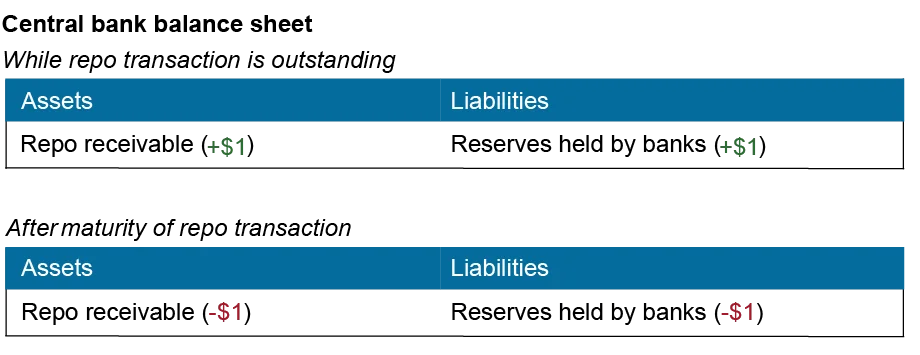
In a typical repo operation, a central bank purchases securities from financial institutions such as banks or dealers and pays with newly created reserves. This sequence not only increases the assets on the central bank's balance sheet but also bolsters the reserves held by those financial institutions. The liquidity supplied lasts only until the transaction matures, at which point the central bank retrieves the securities and reclaims its reserves, thus contracting its balance sheet.
Visual explanation of repo mechanics:

Reverse Repos: Draining Liquidity
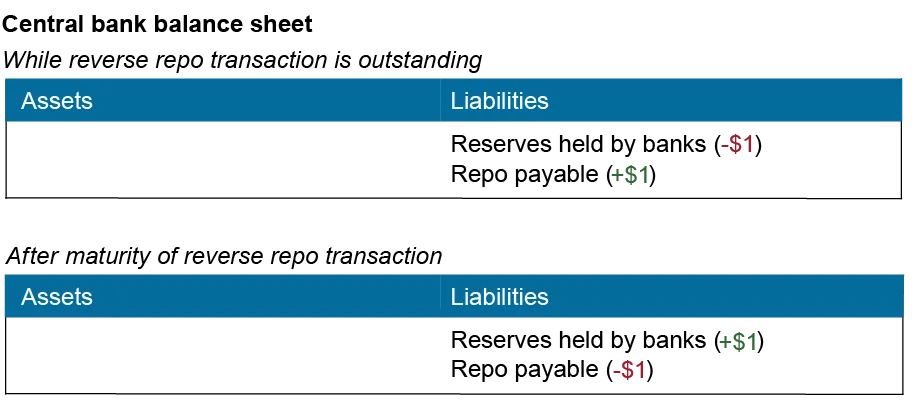
Conversely, reverse repos are employed by central banks to withdraw liquidity from the financial system. By selling securities from their holdings to financial institutions, the central bank effectively converts the reserves it receives into a liabilities entry on its balance sheet. This interaction does not change the total size of the balance sheet, but it alters the composition of liabilities, allowing for tighter control over monetary conditions.

Visual explanation of reverse repo mechanics:
The Federal Reserve's Repo and Reverse Repo Operations
The Federal Reserve's repo and reverse repo transactions occur every business day, serving as tools to maintain short-term interest rates. Daily operations commenced in 2021, transitioning to standing repo operations designed to supply liquidity effectively. The rate for these operations is determined by the Federal Open Market Committee (FOMC), establishing a ceiling on overnight interest rates by providing a competitive funding source. Current operations involve high-quality collateral such as U.S. Treasury securities and agency debts, settling on the same day through a tri-party repo platform.
Repo usage has expanded significantly during key liquidity crises, including notable spikes in September 2019 due to market dislocations and the 2020 pandemic response, reaching unprecedented levels. Recent data reflects ongoing adjustments in repo operations as the banking system navigates complex liquidity environments.
Historical perspective on Federal Reserve repo transactions:

The Evolution of Reverse Repos
Historically, reverse repos have been less frequently utilized than repos by the Fed. The operational evolution began in December 2015 when reverse repo operations with primary dealers transitioned into Overnight Reserve Repo (ON RRP) operations. This change significantly broadened eligibility criteria by incorporating various market participants like money market funds, thereby reinforcing a pricing floor on overnight lending rates. The ON RRP has become a critical tool for influencing liquidity, especially as systemic liquidity surged during the pandemic.
Transformation of Repo Operations Over the Years
The Fed's experience with repos dates to November 1917, when initial operations were authorized to navigate the financial challenges of war financing. Repos quickly became a favored method for offering liquidity to banking institutions, with early repo transactions accounting for over 30% of the Fed's total assets. Over the decades, changing financial landscapes have necessitated adaptations in repo operations, such as altered counterparty eligibility and revised rates. Initially linked to the discount rate, repo rates now correlate with market-driven benchmarks determined by the FOMC.
In 1999, the Fed further diversified the collateral eligible for repos, including agency debt and mortgage-backed securities, alongside enhanced settlement mechanisms through tri-party arrangements—a significant operational shift that improved liquidity management capabilities.
Conclusion: Repo Operations in Contemporary Monetary Policy
Repo operations, as executed by central banks, are essential to maintaining liquidity and establishing stable monetary conditions. The evolution of these tools reflects adaptive responses to economic stresses while illustrating their significance in the overarching framework of monetary policy implementation. As the financial landscape continues to evolve, central banks’ strategies regarding repos will likely undergo further refinement, reinforcing their role in managing both systemic risks and the efficiency of financial markets.
For more detailed insight into repo market dynamics, additional resources can be explored:


