Side A · Liner notes
Simon Property Group's Strategic Retreat: Another Mall Closure amidst Retail Transformation
Banking · Words by Wolf Richter · Released
Simon Property Group is set to relinquish the Philadelphia Mills mall, marking another strategic reduction in its mall portfolio amid shifting retail dynamics.
Simon Property Group (SPG), the premier mall landlord in the United States, is poised to relinquish another property as it navigates through a challenging retail landscape. The company is now in discussions to transfer control of the Philadelphia Mills outlet mall, the second largest in Pennsylvania, back to its lenders. This marks another chapter in Simon's ongoing strategy to shrink its mall holdings, a trend that has been underway for over a decade.
The Philadelphia Mills, which spans 1.7 million square feet, has been struggling financially, exacerbated by a significant decline in foot traffic and a series of store closures. The mall has become emblematic of the broader Brick and Mortar Meltdown, a term used to describe the shift in consumer behavior towards online shopping. As noted by the Philadelphia Business Journal, Simon owes $259 million on the property, which has been in a state of financial distress for some time—especially significant given that the loan matured in June and remains unpaid.
When Simon purchased the mall in 2007 as part of a larger acquisition, it was appraised at $370 million. However, recent city assessments indicate its current value has plummeted to just $101 million, representing a staggering 73% reduction. This depreciation casts a long shadow over the asset’s viability and underlines the mounting pressures faced by physical retail spaces.
Financial Strains and Market Realities
The dynamics surrounding the CMBS (Commercial Mortgage-Backed Securities) associated with this debt illustrate the complexities at play. With the mall’s financial troubles well-documented, Simon's move to hand over the property to lenders could serve as a pivotal moment, not only for the company but also for the commercial real estate market at large. According to sources, the debt management on the mall had involved a convoluted series of extensions, with the original mortgage—a $278 million securitization—taking numerous turns before arriving at the current state of affairs.
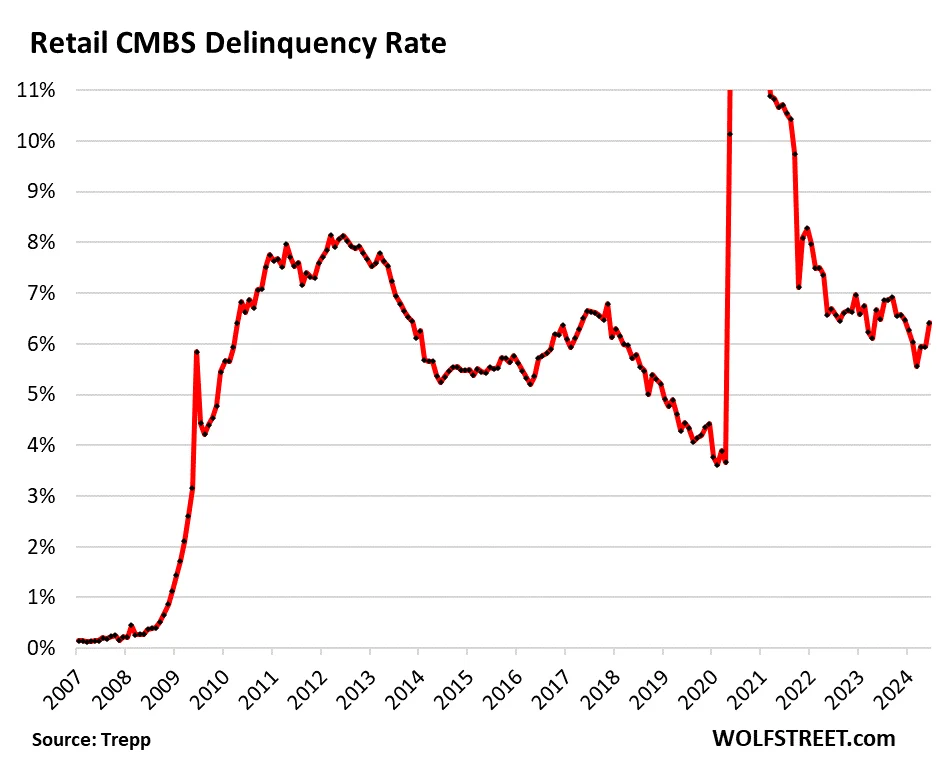
Moreover, the situation at Philadelphia Mills reflects broader concerns shared among mall owners across the country. The CMBS delinquency rate for mortgages secured by mall properties has climbed to 6.4%, indicating widespread distress within the sector. Notably, this rate has surged amid what analysts describe as a "phantom" recovery where traditional retailing is unlikely to return to pre-pandemic levels. The looming expirations of major lease agreements further complicate prospects: anchor tenants like Burlington Coat Factory, AMC Theaters, and Marshalls face critical lease renewals within the next few years, with significant implications for the mall’s financial health.
Jonathan Ramel, a vice president at Morningstar Credit, remarked on the harsh realities of retail recovery. He highlighted prior recovery successes for Philadelphia Mills, but underlined that today’s environment presents far greater challenges. The new landscape is characterized by decreased consumer visits and a shift toward digital platforms, factors which would likely hinder mall loyalty even if major retailers were to stay or attempt to rebound.
Strategic Shifts and Portfolio Management
Simon’s efforts to liquidate underperforming malls are not a sudden decision—they reflect a long-term recognition of market trends. Since 2012, Simon has divested 38% of its shopping centers, translating to a loss of 122 properties out of the 317 it had at that time. This includes not only closures like Philadelphia Mills but also significant alterations to its portfolio through sales and spinoffs, such as the creation of Washington Prime Group in 2014. Washington Prime’s decline culminated in a bankruptcy filing in 2021, serving as a cautionary tale of market misalignment.

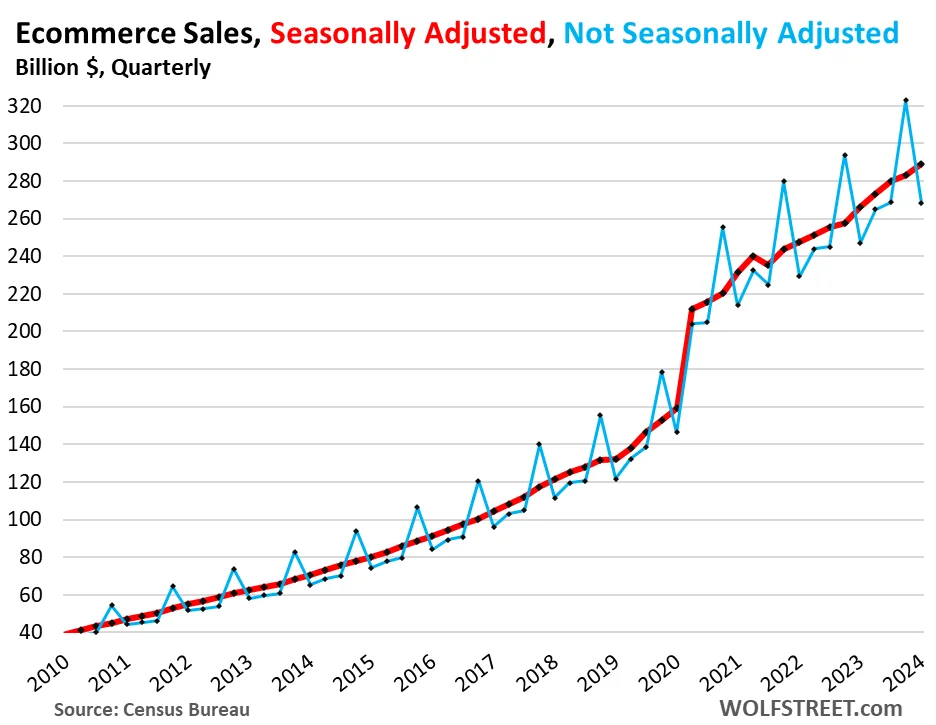
As e-commerce sales soar—up by 90% since the pandemic began—physical retail has been forced to adapt or perish. Data from the first quarter of this year indicated a record $289 billion in e-commerce sales, reflecting a 8.6% increase year-over-year. Caught in this seismic shift, Simon Property Group and other physical retail-centric entities are left reevaluating their business models and tenant relationships.
With substantial challenges mounting, Simon’s decision to exit another mall suggests a prioritization of financial stability over expansive growth. The firm's ongoing conversations with special servicers indicate a systematic approach to managing liabilities, which could define its trajectory going forward. For investors and market observers, this case underscores how companies must stay ahead of transformative retail trends to retain relevance amidst ongoing economic changes.
Looking Ahead
As Simon Property Group faces the difficult task of adapting to a rapidly changing retail environment, the fate of Philadelphia Mills serves as a crucial reminder of the enduring impacts of consumer preference shifts. Stakeholders—including shareholders, mall employees, and surrounding communities—will need to reckon with these changes as they unfold. As discussions continue regarding debt restructuring and property management, the broader question remains: what does the future hold for America’s shopping malls?
With Simon's longstanding experience navigating these turbulent waters, the coming months will be critical in determining if the company can stabilize its portfolio and retain a foothold in an increasingly digital marketplace.


