Side A · Liner notes
Banking System Vulnerability Updates: Key Indicators through 2025
Banking · Words by Matteo Crosignani, Thomas Eisenbach, and Fulvia Fringuellotti · Released
This analysis assesses U.S. banking system vulnerabilities through 2025, examining capital adequacy, liquidity stress, and fire-sale risks based on updated metrics.
Recent research from financial advisors Matteo Crosignani, Thomas Eisenbach, and Fulvia Fringuellotti provides a comprehensive update on the vulnerabilities present in the U.S. banking system, emphasizing the performance metrics through the second quarter of 2025. Drawing on analytical frameworks developed by the Federal Reserve Bank of New York, this evaluation highlights four distinct measures of vulnerability: capital, fire-sale, liquidity, and run vulnerabilities.
Measures of Banking System Vulnerability
The study analyzes vulnerabilities using four measures first articulated in a Liberty Street Economics post from 2018, and these have continued to be refined annually. Updating the methodology in 2023 improved the precision of these measures, utilizing publicly available regulatory data concerning major bank holding companies.
Capital Vulnerability Indexes
The Capital Vulnerability Indexes assess the banking sector's capital position in response to severe economic shocks. Based on the CLASS model, this analysis evaluates how much capital banks would need under two different macroeconomic scenarios: a "2008 redux" reflecting the 2007-09 financial crisis and a "2022 redux" mirroring conditions during the interest rate hikes of 2022.
Results indicated that the capital gap under the "2008 redux" scenario is currently $1.92 billion, a notable drop from $5.1 billion in 2024:Q2. Similarly, under the "2022 redux," the gap is now $161.32 billion, down from $260.47 billion a year prior. This progressive improvement correlates with banks maintaining higher capital ratios than historical averages, further stabilizing the financial landscape.
The evolution of the Capital Vulnerability Index illustrates the relationship between a bank's starting capital and depletions of that capital over time, particularly in light of unrealized gains and losses on securities. Since 2023, bank capital levels have steadily increased, amplifying the stability of financial institutions.
Fire-Sale Vulnerability Index
The Fire-Sale Vulnerability Index, based on systemic risk assessments, gauges how well-positioned banks are to resist a uniform shock impacting asset values. This metric assumes that banks, under duress, will sell off assets to manage leverage, resulting in cascading spillover losses calculated as a fraction of Tier 1 capital. As banks' securities are adjusted for unrealized losses, heightened leverage reflects increased vulnerability during periods of market stress, such as those seen in early 2022.
While the index has remained relatively stable compared to the previous assessment, it has shown notable fluctuation since early 2022, peaking in late 2022 at levels echoing those observed in 2009. Since then, the index has slightly retraced its course, indicating resilience, but it remains higher than the average levels seen between 2015 and 2022. The components of this index reflect a complex interplay among the banking system's size and leverage alongside interconnectedness with market liquidity.
Liquidity Stress Ratio
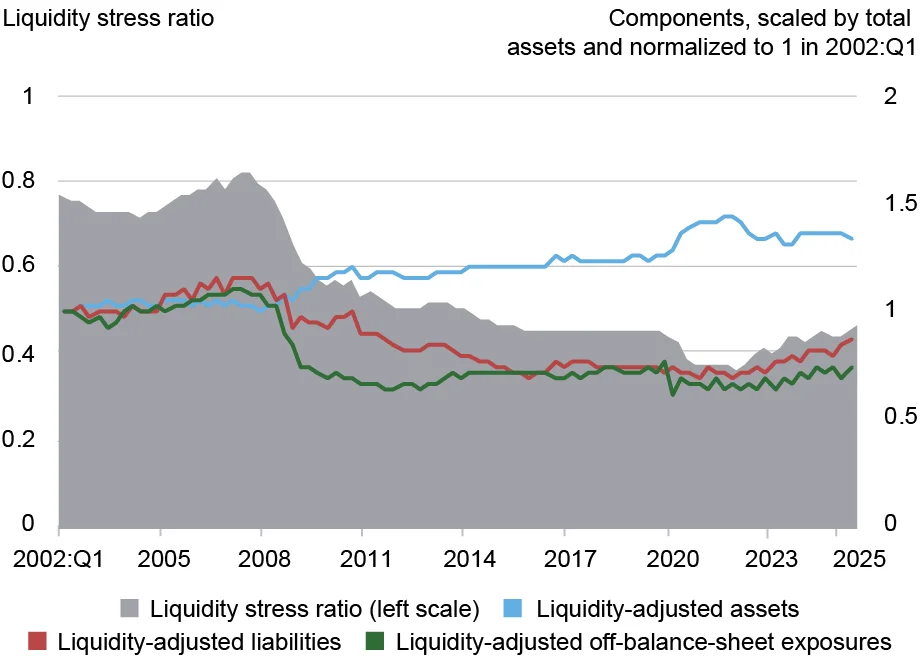
The Liquidity Stress Ratio measures potential shortfalls in liquidity under stressed conditions, examining the mismatch between expected outflows and inflows on the asset side. This ratio prioritizes the adjustment of liabilities and assets for their liquidity profiles, reflecting the banks' ability to cover liabilities amid market fluctuations.
Presently, the Liquidity Stress Ratio stands above the previous year's level, having escalated steadily since early 2022 and aligning closely with pre-pandemic values. Despite this, it remains moderate in a historical context, approximately half of its peak during the 2007 financial crisis. A detailed decomposition reveals declines in liquid assets while unstable funding and off-balance-sheet exposures have contributed to the increased ratio.
Run Vulnerability Index
This index evaluates the risk banks face of bank runs, factoring in both liquidity and solvency amidst unfavorable economic events. The methodology identifies the minimum necessary fraction of unstable funding to prevent insolvency under adverse conditions.
Currently, the Run Vulnerability Index mirrors prior assessments, remaining moderate compared to historical standards yet elevated relative to the calmer periods recorded between 2015 and early 2022. The increase since 2022 primarily stems from heightened leverage, with contributing factors including unstable funding and the quality of liquid assets.
Final Assessment
In summary, the findings present a nuanced view of vulnerabilities in the U.S. banking sector as of mid-2025. While key vulnerability indicators have dropped substantially from the heights seen before the 2008 financial crisis, some measures continue to reflect higher risks compared to the stable conditions observed from 2015 to 2020. Ongoing monitoring and analysis will be critical as economic conditions evolve and volatility persists across financial markets.
Authors

Matteo Crosignani is a financial research advisor in the Federal Reserve Bank of New York’s Research and Statistics Group.

Thomas M. Eisenbach is a financial research advisor in the Federal Reserve Bank of New York’s Research and Statistics Group.

Fulvia Fringuellotti is a financial research economist in the Federal Reserve Bank of New York’s Research and Statistics Group.


