Side A · Liner notes
Assessing Treasury Market Liquidity Amid Economic Shifts in 2025
Markets · Words by Thomas Jones · Released
In 2025, the U.S. Treasury market faced liquidity fluctuations influenced by interest rate cuts and trade policy changes, with notable impacts around April's tariff announcements.
The U.S. In 2025, the intersection of reduced interest rates, abrupt trade policy shifts, and increasing economic uncertainty has created notable challenges for Treasury market liquidity. This analysis revisits several key metrics to evaluate how liquidity has fared under these conditions.
Understanding the Importance of Treasury Market Liquidity
Liquidity in the Treasury market is vital for multiple stakeholders, including the Treasury Department, the Federal Reserve, and various financial institutions. It enables seamless transactions and management of interest rate risk. Therefore, developments affecting liquidity directly impact the functioning and stability of the broader economy.
Defining and Measuring Liquidity
Market liquidity refers to the ease with which an asset can be converted to cash without significantly impacting its price. For this analysis, we utilize three key measures derived from high-frequency interdealer data: the bid-ask spread, order book depth, and price impact. These metrics focus on the most actively traded Treasury securities—namely, the two-, five-, and ten-year notes—using New York trading hours (7:30 a.m. to 5 p.m., Eastern Time).
Liquidity Changes Observed in April 2025
In April 2025, significant turns in bid-ask spreads indicated a temporary decline in liquidity. The June 2025 tariff announcements led to a notable widening of the bid-ask spreads, with levels escalating comparably to past periods of market stress, such as the COVID-19 pandemic in March 2020 and the banking turmoil in March 2023. However, these spreads contracted following the April 9 announcement postponing some tariffs, ultimately aligning back to the norms established in recent years.
Bid-Ask Spreads Analysis
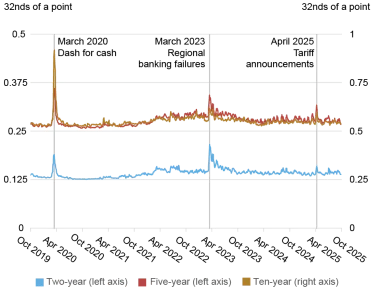
The chart illustrates five-day moving averages of average daily bid-ask spreads from October 2019 to September 2025.
Another indicator, the order book depth—the average quantity of securities available at the best bid and offer prices—similarly reflected liquidity concerns in April 2025, dipping to its lowest level since March 2023. A swift recovery followed, with order book depth showing improvements by late summer 2025, nearing levels not seen since the Federal Reserve's tightening began in March 2022.
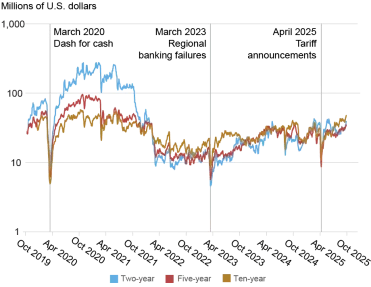
Data from October 2019 to September 2025 indicating shifts in order book depth.
Additionally, the price impact metric, which assesses the effect of trades on security prices per $100 million in net order flow, exhibited a marked deterioration in April 2025. Price impact surged following the tariff announcement, but reverted to more stable levels by late summer, indicating a subsequent bolstering of liquidity.
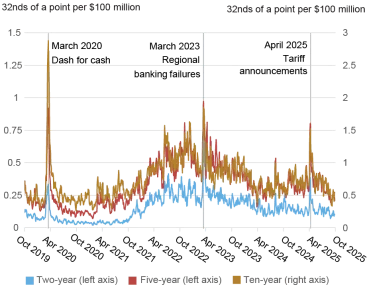
Price impact metrics tracking from October 2019 to October 2025.
Volatility Correlation with Liquidity
The relationship between liquidity and volatility has been documented extensively. Increased volatility typically leads market makers to widen bid-ask spreads and reduce order book depth. A key moment in 2025 came with peaks in price volatility after the April 2 tariff announcement, reaching its apex from April 7 to 9, before declining in response to the postponement announcement on April 9.
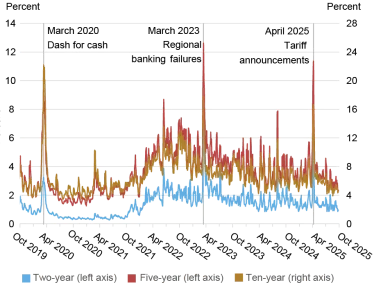
Volatility trends observed from October 2019 to October 2025.
Assessing the Relationship Between Liquidity and Historical Trends
Comparative assessments between price volatility and liquidity measures reaffirm that 2025's liquidity patterns align with historical trends. Scatter plots of price impact against volatility for the five-year note confirmed that the October 2025 observations remained consistent with past relationships. This aligns with historical analyses while underscoring the importance of ongoing trend monitoring.
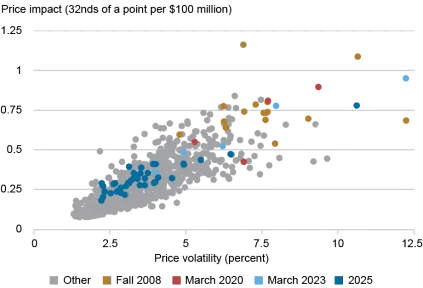
Observed trends from 2005 to 2025 illustrating liquidity and volatility relationships.
Ongoing Vigilance Required for Treasury Market Liquidity
While recent assessments suggest that Treasury market liquidity is operating within expected bounds given prevailing volatility levels, it is subject to significant oversight. With Treasury debt expanding against a backdrop of limited dealer capacity, market liquidity will continue to face pressures. Policymakers have initiated measures to enhance market resilience, yet the ongoing developments could influence overall market functioning and liquidity.
In summary, investors and financial institutions should closely monitor these liquidity metrics as they provide essential insight into the health of the Treasury market, indicative of broader economic conditions.
Michael J. Fleming is the head of Capital Markets at the Federal Reserve Bank of New York’s Research and Statistics Group.


