Side A · Liner notes
How Banks Leverage Nonbank Structures for Enhanced Liquidity Management
Banking · Words by Nicola Cetorelli and Saketh Prazad · Released
Banks are diversifying into nonbank activities to optimize liquidity management, evidenced by significant intracompany financing trends and strategic adaptations.
Over the past several decades, U.S. banks have transformed from traditional institutions focused solely on deposits and loans into diversified operators that integrate a range of nonbank activities. This transition is largely motivated by the need to manage liquidity more efficiently. As explored in a recent analysis, banks are using their nonbank subsidiaries to enhance liquidity management, particularly in times of stress.
Managing Liquidity Risks Through Diversification
The essence of financial intermediaries lies in their susceptibility to liquidity risk. A notable research paper highlighted that banks could better manage their liquidity by combining deposit and credit functions. This strategy works well because unexpected fluctuations in deposit withdrawals and credit demands tend to be imperfectly correlated. Consequently, it enables banks to minimize their overall liquidity holdings compared to organizations that separately focus on either deposits or lending.
This framework applies not only to traditional banks but also to diversified U.S. banking firms, known as bank holding companies (BHCs), which encompass both bank and nonbank subsidiaries. The reduction in liquidity demands faced by these affiliated entities allows BHCs to maintain lower liquidity buffers, enhancing their overall liquidity risk management. Data from the study titled “The Nonbank Footprint of Banks” indicates that banking firms with a broader nonbank presence can better meet their liquidity needs.

Intracompany Support for Liquidity
An important characteristic of effective liquidity management is the mutual support between bank and nonbank subsidiaries within a BHC. This mutual assistance manifests through substantial intracompany borrowing and lending processes. For example, a significant proportion of commercial bank assets is financed through intracompany loans from affiliated nonbanks, while commercial banks also provide funding to their nonbank counterparts.
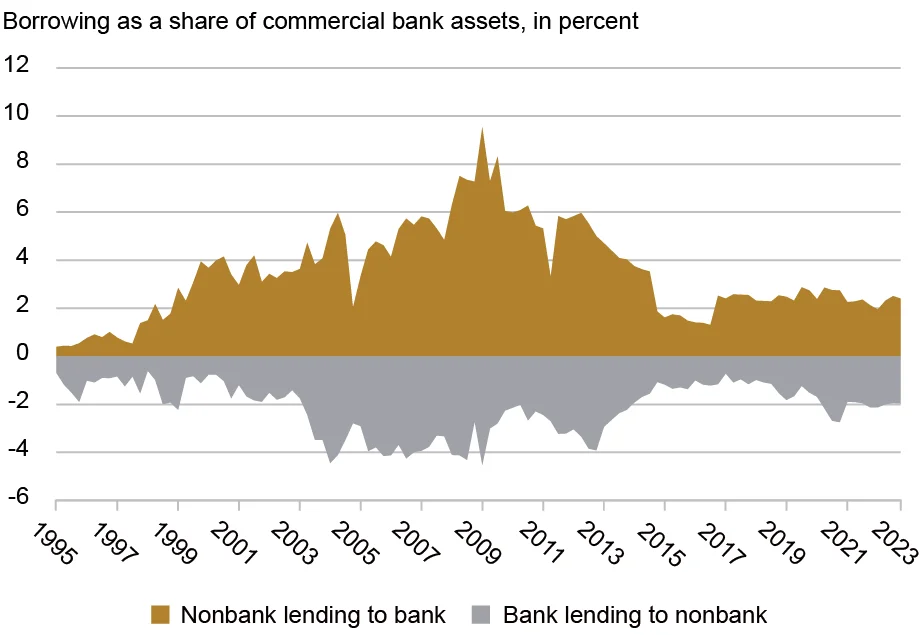
On average, these intracompany transactions represent about 5% of bank subsidiaries’ total assets, underscoring their economic significance. It provides strong evidence for the active liquidity support extended between affiliated banking and nonbank entities.
Support During Stress Periods
The nature and volume of these intracompany transactions offer insights into whether BHCs leverage their nonbank footprints as part of a deliberate liquidity strategy. An investigation is warranted to determine if such internal funding practices increase during times of heightened liquidity needs.
A pivotal case study occurred during the liquidity shock of the summer of 2007, amidst distress in asset-backed commercial paper (ABCP) conduits. This distress created varying levels of liquidity exposure among commercial banks, specifically those heavily invested in ABCP. A comparative analysis revealed that banks heavily exposed to these conduits markedly increased borrowing from their nonbank affiliates.
Interestingly, these banks also reduced their reliance on the Federal Reserve’s emergency liquidity facilities, suggesting that funding from nonbank subsidiaries mitigated their need for external support. Preliminary calculations indicate that funding from nonbanks could have cut down Federal Reserve borrowing by approximately $176 billion, which is quite significant given that total borrowings from the Fed peaked at around $700 billion during the financial crisis in 2008.
The Impact of Regulatory Changes
A core question arises: do BHCs expand their nonbank operations primarily to capitalize on liquidity synergies? To test this theory, researchers looked at how regulatory frameworks affect the internal funding dynamics between bank and nonbank subsidiaries. A significant regulatory shift occurred with the implementation of the Dodd-Frank Act, which mandated that certain BHCs prepare “living wills” detailing their resolution strategies. This regulation explicitly discouraged interdependency in funding between bank and nonbank subsidiaries, leading to a presumed decline in the value of internal funding operations.
Following this regulatory shift, banks reported adjusting their internal funding practices. For instance, Goldman Sachs noted its efforts to minimize internal transactions that transfer risk across its entities in its 2015 resolution plan. Similarly, J.P. Morgan indicated moves to simplify interconnected funding relationships in its 2019 plan.
A comparative analysis of BHCs subject to the living wills regulation and those exempt revealed noticeable reductions in their nonbank footprints across four measures: nonbank subsidiary assets as a share of total BHC assets, the number of nonbank subsidiaries, unique nonbank activities, and the size of intracompany funding flows. Post-regulation results consistently indicated decreased metrics for those impacted by the regulatory “treatment,” signifying a strong link between liquidity provision and the retention of nonbank subsidiaries.
Conclusions
The evolution of U.S. banking institutions has shown a clear trajectory toward integrating nonbank financial services into their operational frameworks. As discussed, this expansion reflects a governing principle of liquidity management in the contemporary banking environment. Efficient liquidity practices lead BHCs to either acquire or divest nonbank subsidiaries based on their contributions to liquidity services.
Additionally, this trend invites contemplation about regulatory implications. Restrictions surrounding bank activities may inadvertently incentivize a shift of financial intermediation toward nonbank structures outside traditional boundaries. Importantly, banks remain vital liquidity sources, even to unaffiliated nonbank entities, potentially complicating the operational landscape. Thus, it becomes apparent that the intent to segregate banking operations through regulation may not effectively eliminate associated risks; instead, such risks could emerge in new, less transparent contexts.


