Side A · Liner notes
Examining the Trends and Metrics of Global R* Post-Pandemic
Banking · Words by Robert Rodriguez · Released
This analysis explores the recent changes in global and U.S. r*, highlighting the significant rise following the COVID-19 pandemic and its implications.
Recent analyses from Marco Del Negro, Elena Elbarmi, and Michael Pham present a refined understanding of the global neutral interest rate, r*, utilizing data on yields and inflation from various countries. This model, adapted from the findings in “Global Trends in Interest Rates,” reveals an important evolution: following a substantial decline from the 1990s to pre-COVID times, global r* has seen an increase but remains markedly lower than pre-1990 levels.
Is There a Global R*? Cross-Country Convergence
Data visualizations including estimates of r* across eighteen developed nations underscore a pivotal transition: prior to the late 1980s, significant variation existed in r* across these countries. However, post-1980s financial market integration led to a noteworthy convergence in r* figures, allowing for the consideration of a unified global r*. This convergence implies that shifts in r*—namely its decline leading up to the pandemic and its subsequent rise—are phenomena affecting advanced economies collectively rather than merely under unique national circumstances.

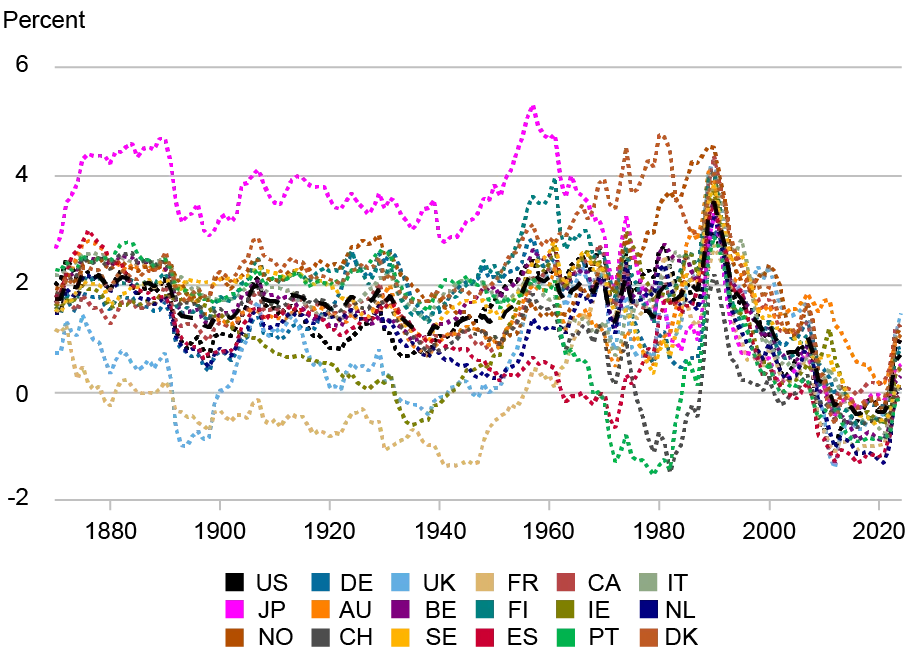
Notes: This chart shows r* estimates for countries including Australia, France, Japan, and the U.S., reflecting convergence patterns observed post-1980s.
The Decline, and Recent Rise, in Global and U.S. R*
The analysis illustrates a significant decline in global r*, measuring approximately 3% in the early 1990s to below zero post-financial crisis, continuing into the 2010s. Interestingly, a rebound of about one percentage point has been noted in the aftermath of COVID-19. As of 2024, median estimates place global r* around 0.5%, precisely at 0.31% for global and 0.46% for U.S. r*, which aligns closely with broader GDP-weighted averages for ongoing estimates drawn from major economies.
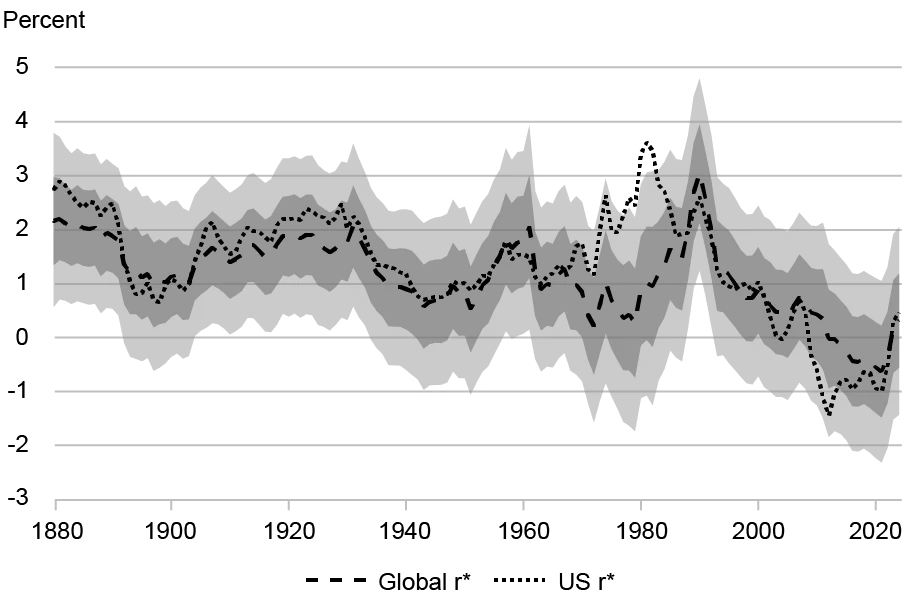
Notes: This graph showcases the tracking of U.S. r* against global trends since the late 1980s.
Although the estimated levels of r* remain fraught with uncertainty, the methodological model employed is adept at capturing r* changes over time with solid statistical confidence. From 1990 to 2019, the decline in global and U.S. r* is calculated at around 3.5 percentage points. Statistically, the probability of this decline being less than zero exceeds 97.5%, suggesting a clear downward trend.
Pre- and Post-COVID Changes in R*
| Global R* | U.S. R* | |||
| 1990-2019 | 2019-2024 | 1990-2019 | 2019-2024 | |
| Baseline model | ||||
| r* | -3.52*** | 0.79*** | -3.27*** | 1.11*** |
| (-4.94, -2.09) | (0.07, 1.49) | (-5.13, -1.36) | (0.18, 2.06) | |
| Convenience yield model | ||||
| r* | -3.83*** | 1.01*** | -3.11*** | 1.14*** |
| (-5.41, -2.27) | (0.30, 1.70) | (-4.45, -1.75) | (0.42, 1.86) | |
| cy | -1.58*** | 0.35 | -0.85** | 0.49* |
| (-2.64, -0.50) | (-0.17, 0.86) | (-1.57, -0.11) | (-0.05, 1.03) | |
| Other | -2.36*** | 0.65** | -2.26*** | 0.65** |
| (-3.55, -0.98) | (0.08, 1.22) | (-3.55, -0.98) | (0.08, 1.22) |
Notes: Values indicate the statistical significance of changes in trends for both periods.
The surge in r* in the post-COVID landscape—estimated at about 0.8 percentage points for global and over 1 percentage point for the U.S.—stresses that while increases have occurred, they do not compensate for the more considerable declines experienced prior. With r* still significantly below 1990s levels, the question surrounding its driving forces becomes pertinent. This rise is not exclusive to the U.S.; thus, potential factors must be global.
Historical trends noted in previous research suggested that a rise in the global convenience yield—reflecting demand for safety in government bonds—was crucial to the pre-COVID period decline in r*. Conversely, the post-2019 uptick could be seen as influenced by a decline in that yield, contributing one-third to one-half of the increase in r* during the recent timeframe. Significantly, the decline is testified by tighter corporate bond spreads, hinting at a lessened safety appeal of government bonds attributed to growing debt concerns among advanced economies.
Exploring Other Drivers of Rising R*
What then lies beyond the convenience yield as an explanation for the post-pandemic rise in r*? Prominent scholarly discussions suggest two key considerations: one links a potential surge in productivity driven by artificial intelligence, while the other contemplates increasing debt-to-GDP ratios stemming from a reluctance among established economies to elevate tax bases in response to demographic transitions and anticipated escalations in military expenditures. While Rachel's paper offers insights on these elements, their collective impact on r*’s abrupt rise remains challenging to fully reconciliate within traditional models.
In conclusion, while the increase in r* represents a notable shift in economic conditions following the pandemic, a comprehensive understanding necessitates further exploration into both global conventions and local economic matters. The estimations revisited in this post, along with methodologies employed, remain available on our GitHub page for continued research updates.


