Side A · Liner notes
Understanding the Case for Aggressive Venture Investing After Achieving Financial Independence
Markets · Words by Financial Samurai · Released
This article explores the rationale behind aggressive venture investing post-financial independence, balancing financial strategy with psychological motivations.
After sharing my experiences of feeling stressed and exposed financially, I received a fair amount of criticism suggesting that I was being irresponsible and reckless. These remarks pushed me to re-evaluate my risk profile and articulate my reasoning behind my investment strategies, both financial and psychological.
I face a liquidity problem, but not a solvency issue. Understanding this distinction is crucial — liquidity impacts cash flow, while solvency concerns assets exceeding liabilities, a more severe issue that could lead to foreclosure or bankruptcy. I hope this analysis encourages you to think critically about your own risk profile, as asset allocation can subtly drift over time based on market conditions and personal circumstances.
My Venture Investing Philosophy Post-Financial Independence
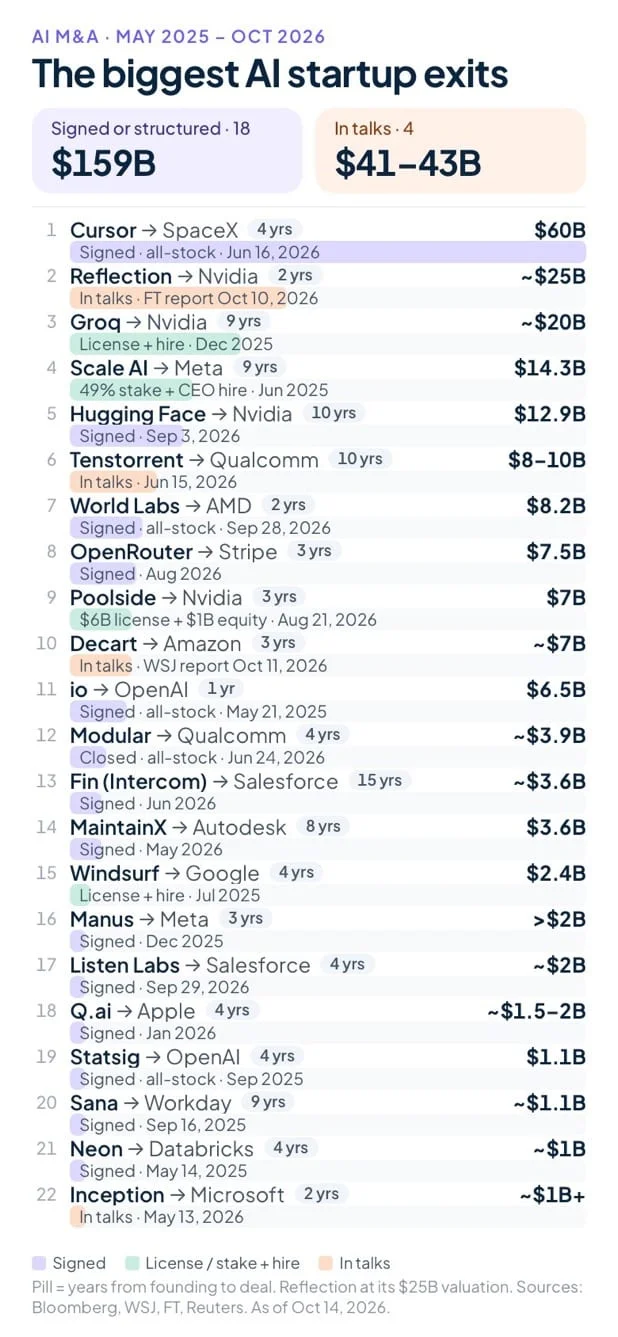
Since exiting the labor force in 2012, I observed that the rise of AI threatens my ability to earn supplemental retirement income. To actively combat inflation, I feel compelled to invest aggressively until my free cash flow diminishes. If AI poses existential risks to job security, it stands to reason that I should hold stakes in companies driving this transformation.
Having invested since 1996, I have weathered multiple market downturns, including a 35% to 40% net worth loss within six months during the global financial crisis. This traumatic experience highlighted that adhering to a risk-appropriate allocation isn't merely a suggestion; it's essential for survival. Therefore, I limit private investments to 20% of my investable assets. This allocation includes venture capital, venture debt, and angel investing — which are known for their opacity, illiquidity, and often elevated fees. Nevertheless, I find value in the potential for higher returns and the outsourcing of the decision-making process.
Moreover, I cap my public and private equity exposure at 50% of my net worth to reduce volatility, which is particularly vital at my stage of life. My goal is to outperform average index investors, which would be difficult by specializing solely in the same assets they do. I also aim to remain unemployed until my youngest child reaches adulthood in twelve years. If my private investment assets were to collapse, my overall finances would still stabilize given that I reserved 80% of my capital from this risk. While correlations between private and public markets exist, this protective buffer allows me to maintain discipline in asset management.
Recent Capital Calls and Market Dynamics
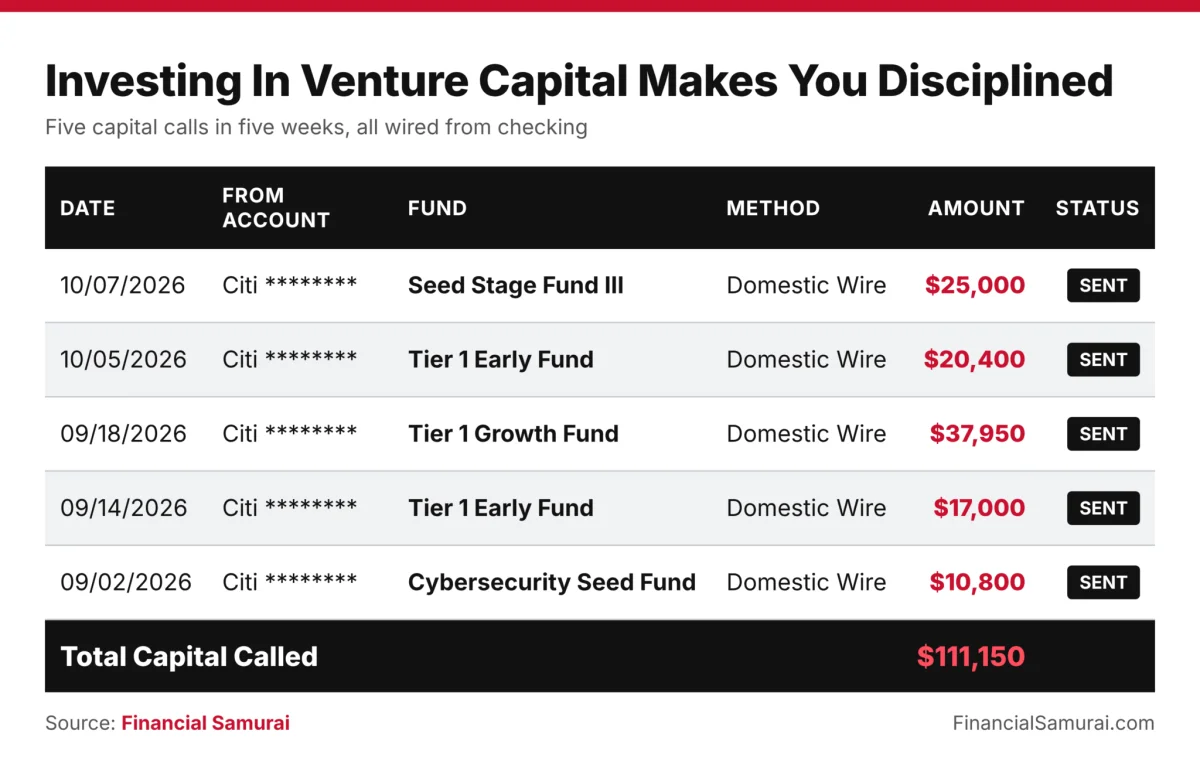
Illustrating the intensity of my capital commitments, I recently faced five capital calls over five weeks, totaling $111,150. This amount significantly exceeds my passive income and online revenue, inducing a degree of financial constraint. Even high-earning professionals, such as a Managing Director at an investment bank with a $1.5 million annual income, would feel the weight of such requests due to the structure of their compensation.
Capital calls can serve as both a signal of prosperity and a potential indicator of bubble-like behavior in private markets, arising from excess liquidity pursuing limited high-quality investments. My budget is stretched each time I face substantial funding requests, leading to necessary sacrifices that, albeit stressful, keep me engaged in the investment process.
Advantages of Aggressive Venture Investing
Before proceeding with any investment, I invest considerable time in assessing the risk-reward landscape and benchmarking my liquidity position. Each allocation has a defined purpose; if I cannot reason why I'm investing a given dollar, I choose not to invest it. Furthermore, discussions with my wife and father — and the Financial Samurai community — help me clarify and validate my decisions through diverse perspectives.
1) Guarding Against Self-Induced Risk
During my trading days, I frequently made 1,000 trades annually, resulting in swings of tens of thousands of dollars. This futile cycle prompted my former boss to intervene. Shifting from that trading lifestyle, I became primarily a buy-and-hold investor focusing on index funds and select stocks. Nevertheless, I've still made regrettable trades that have cost me dearly. As such, I consider my commitment to venture investing less risky; the funds I allocate are tightly controlled and managed by general partners (GPs) who have a vested interest in finding lucrative opportunities.
Involvement in venture capital means I don’t have the temptation to trade these commitments. Since selling any part of that investment is not an instantaneous process, my capital is safe from impulsive decisions that often accompany daily trading.
2) Ensuring Continued Investment During Economic Downturns
Back in 2009, I recognized the opportunity to purchase rental properties during a significant market decline but hesitated due to fear and inconvenience. In 2012, I grappled with selling my home due to concerns about future property values. Fortunately, the property eventually sold at a considerably higher price in 2017. This history guides my current mindset: venture capital commitments require me to invest over time irrespective of market conditions.
Funds generally request roughly 90% of committed capital over a span of three to five years, forcing consistent investment even when market sentiment is poor. Historically, declines in major indices like the S&P 500 have led to eventual recoveries and new all-time highs, but acting on these insights while the market is distressed can be daunting. Capital calls help enforce disciplined investment habits that I might abandon otherwise.
3) Investing in Top-Tier Venture Firms for Optimal Returns
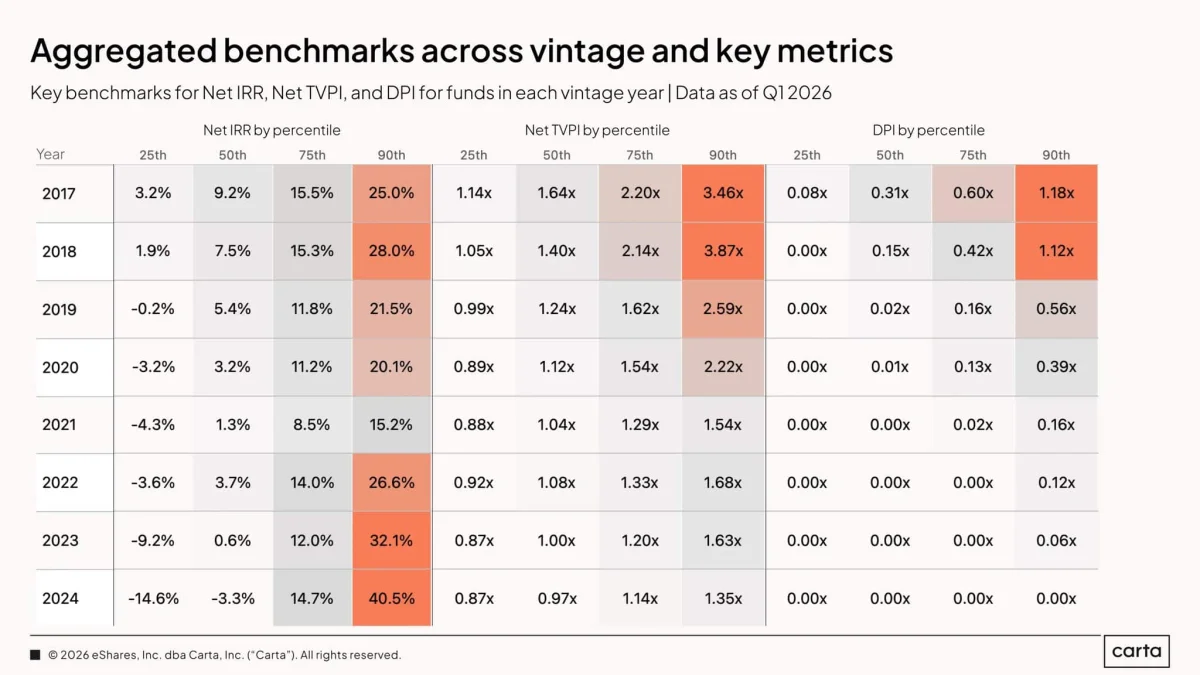
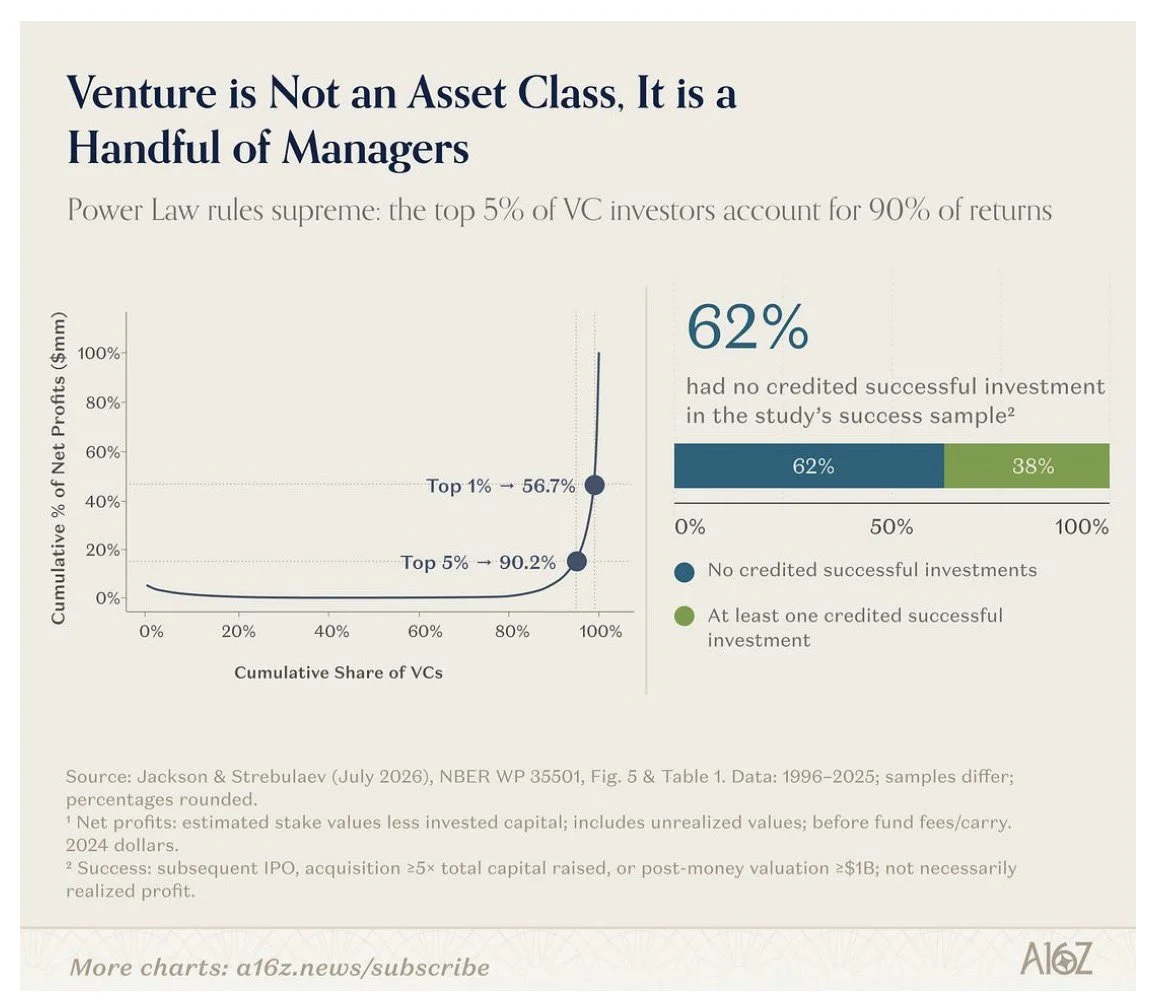
Although many venture capital firms have struggled to outperform the NASDAQ in the past decade, those positioned in the top tier have consistently yielded superior returns. Securing an investment in a distinguished venture fund is an opportunity not to be missed, assuming you can access it. For instance, I was able to invest in a leading fund’s 2026 vintage after participating in its previous vintages. The current portfolio is showing promise, although these returns are not realized until exits occur. Nonetheless, positive valuations mitigate my fears of missing the boat.
The Underexplored Psychological Aspect of Investing
Beyond financial calculations, there’s a hidden psychological component often overlooked. Finding contentment in risk-taking stems from my past experiences with severe hardships. These experiences lead me to a point where any advancement — be it career, relationship, or financial — becomes a significant win. This outlook helps me embrace risk as I can tolerate losses, given that my life circumstances were once far more precarious.
A Commitment to My Children's Future
Recognizing the dwindling prospects for my own income, I’m increasingly focused on ensuring my children have the opportunities that may escape them due to disruptive technology, like AI. The conversations I hear from industry executives regarding job losses often fuel my determination to invest aggressively on their behalf, even in the face of potential liquidity challenges. The discomfort I feel with my finances is offset by hope that my investments will appreciate when my children transition into adulthood, providing them with a buffer when they need it most.
As a parent, my sacrifices — both financially and emotionally — are directed towards safeguarding their future. Funding commitments feel meaningful as they symbolize my protective instincts as a father, akin to a parent ensuring their children are taken care of.
Evaluating Risk Exposure
While I apply a 20% cap on my private investments, questions linger over whether this threshold is adequate. Historical performance suggests investing in the S&P 500 and NASDAQ often trumps alternative investments long-term. Nevertheless, those with high-value portfolios may find a significant downturn markedly alters their risk tolerance and emotional responses.
Real estate serves as a stabilizing force in my investment strategy, as it is less liquid; I’m not swayed by market volatility when I can’t see my property's value shift on a daily basis. The long-term horizon I take with real estate helps mitigate impulsive decision-making and aligns with my investment philosophy.
Celebrating the Benefits of Life in America
My life experiences abroad have instilled a deep appreciation for the opportunities available in America. The country’s blend of freedom, rule of law, and entrepreneurial spirit fosters a remarkable environment for success. However, it’s easy to become complacent when life is smooth sailing, leading to missed opportunities. Just as venture capital captures the essence of American entrepreneurship, I find immense value in backing individuals willing to challenge the status quo, while maintaining investments in solid, established market leaders.
Living through the rhythm of capital calls is difficult but not without merit. The aim remains clear: build a significant financial safety net for my children before they grow into adulthood. Critics label my approach as erratic, yet I perceive it as the pragmatic pursuit of a father's unconditional love for his family. This dual-timeline perspective drives every investment decision I make, situating both my children’s present and future needs at the forefront.
Reader Engagement
Is investing 20% of capital in private ventures too aggressive for those with young children? What do you consider a suitable limit? Have you ever made emotional investments motivated by the desire to provide for your family? And do capital calls promote a more disciplined investment approach or simply contribute to stress?
Assess Your Risk Profile
Portfolios can drift significantly over time without intervention. A growing stock market might turn an investor's traditionally balanced asset allocation into a heavily weighted one without their consent. If you’ve got over $100,000 in investable assets, consider pursuing a complimentary financial consultation with a professional who can help adjust your allocations to align with your risk tolerance.
Staying ahead of potential shifts in the market will always be more cost-effective than reacting after the fact.
In considering the larger implications, my goal remains to enlighten others through my investments and experiences. Aligning with my circumstances since 2009, I aim to share insights rooted in firsthand encounters in investing.


