Side A · Liner notes
Millennials and Financial Coping Strategies: How Younger Generations Manage Rising Costs
Banking · Words by PYMNTS · Released
A recent report reveals that 23% of Bridge Millennials are employing four or more financial coping strategies amid rising living costs, illustrating generational differences in money management.
As rising living costs continue to present challenges, a notable 23% of Bridge Millennials are employing four or more financial coping strategies, according to the report "Generations Under Pressure: How Younger Consumers Are Coping With Higher Living Costs." This report, produced by PYMNTS, utilized survey data from 2,747 U.S. consumers to provide insights into the varying tactics adopted by different age groups in response to economic pressures.
Despite this increase in financial management efforts, a paradox emerges; fewer Americans believe their coping strategies are effective. In January, only 25% of consumers reported that their methods were extremely or very effective, down from 34% in October 2025. This suggests that the ongoing strain of managing monthly expenses extends beyond inflationary pressures alone—an indication of the enduring struggle against recurrent financial obligations.
A Generational Divide in Financial Management
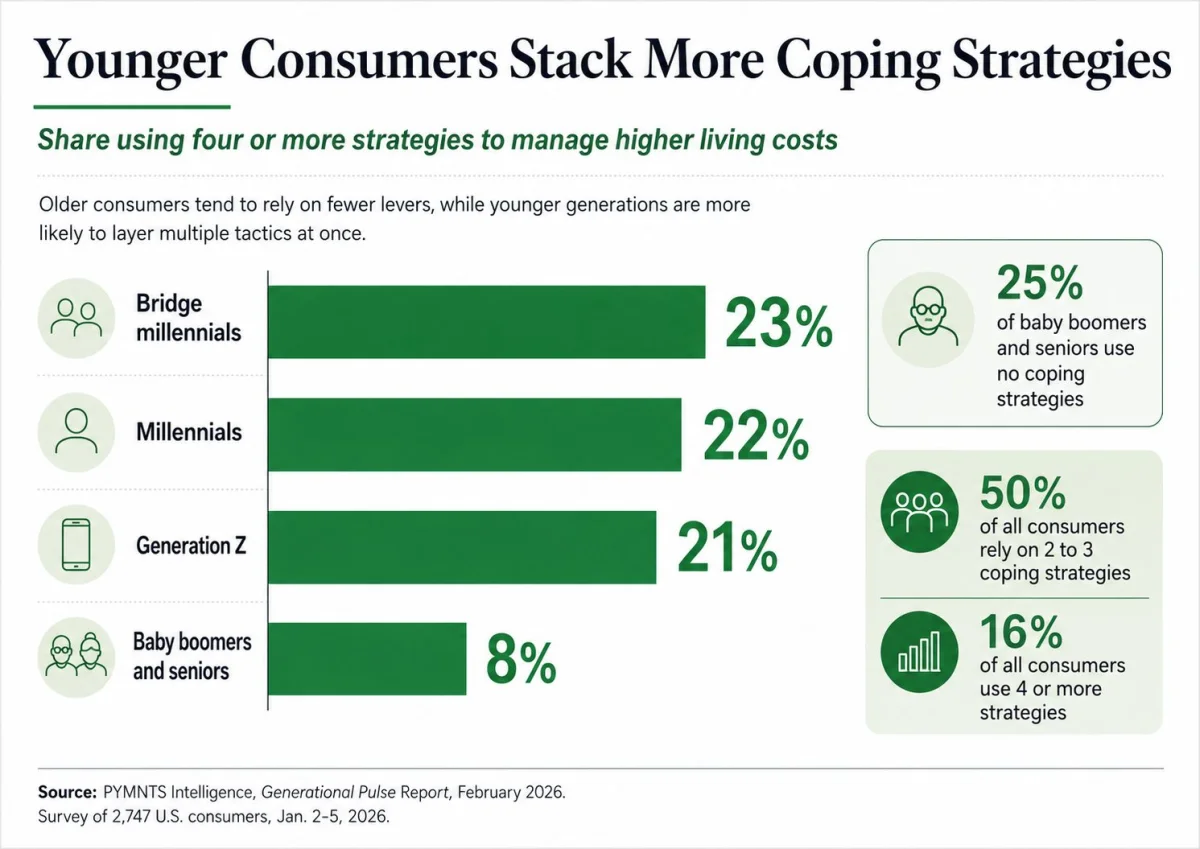
Generational disparities are evident in how different age groups react to financial challenges. Younger consumers, particularly Bridge Millennials and Gen Z, adopt multiple coping strategies, layering efforts like blankets against the chill of rising expenses. You might see them cutting back on discretionary spending while simultaneously seeking additional income sources. In contrast, older generations show a tendency to rely on fewer strategies or none at all. For instance, only 8% of Baby Boomers and seniors utilize four or more coping methods, with a striking 25% of these older individuals reporting that they don't engage in any coping strategies at all.

- Among younger consumers, the practice of utilizing four or more coping strategies is more prevalent: 23% of Bridge Millennials engage in multiple methods, along with 22% of traditional Millennials and 21% of Gen Z. These numbers indicate a marked difference in behavior, reflecting the urgency of their circumstances.
- Older consumers exhibit a more passive stance, with 25% opting out of any coping strategies, indicating a significant gap in how different generations respond to financial pressures. This might stem from varying financial literacy levels or simply a different experience with economic instability.
- The declining confidence in the effectiveness of coping strategies among all consumers underscores that simply increasing efforts hasn't translated to a greater sense of control over their financial situations. Many are left feeling overwhelmed despite their attempts at management.
Understanding the Pressure Points
The survey revealed that younger demographics, particularly Bridge Millennials, average about 3.5 different cost challenges, while traditional Millennials face approximately 3.4. This stands in stark contrast to Baby Boomers and seniors, who report an average of only 2.6 cost pressures. You could argue that this indicates a generational shift towards a more complex financial reality for youth today. Consequently, younger households often piece together a financial strategy that incorporates various smaller actions, rather than relying on singular solutions.

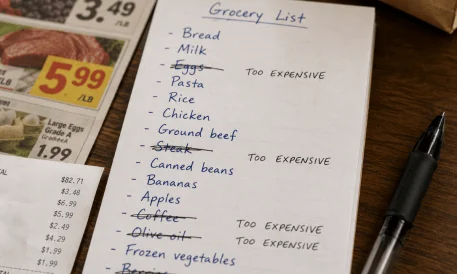
A closer look at specific financial stressors highlights that grocery expenses have surged to a notable 89% among all consumers, indicating widespread concern regarding food costs, a significant burden in household budgeting. Rising prices at the supermarket can siphon off funds that would otherwise cover essential bills. Additionally, healthcare-related pressures have amplified across age groups. You'll find older consumers grappling with escalating insurance premiums and other medical costs, while Gen Z faces strains from increasing expenses related to prescriptions and mental health services. This intergenerational overlap illustrates how widespread financial insecurity impacts multiple age groups.
Opportunity for Financial Tools
While the outlook looks challenging for many, it also opens doors for financial tools that can help consumers better manage their cash flow. As younger generations become more deliberate in their financial decisions, platforms and services offering enhanced visibility, flexibility, and improved timing around recurring expenses stand to gain traction. This could mean a growing market for budgeting apps, financial planning software, or other digital tools designed to help consumers regain a sense of equilibrium amidst ongoing financial challenges.
With financial technology evolving rapidly, this can be a double-edged sword. The proliferation of services could lead to great options for consumers, but it also risks overwhelming them with choices. If you're working in this space, keep an eye on which tools genuinely deliver value and which simply add to the noise. The demand for clarity in financial management is evident.
Future Outlook and Implications
As younger consumers navigate a complex financial environment, their proactive strategies reflect a necessary adaptation to economic realities. Understanding these generational differences in approaches to financial management not only provides insight into consumer behavior but could inform the design and marketing of financial solutions tailored to meet these evolving needs. The long-term implications are profound—if younger generations maintain a low confidence level in their strategies, it could hinder their financial resilience and affect consumer spending behaviors in the broader economy.
In light of these pressures, companies looking to engage with younger consumers will need to rethink their offerings. This isn’t just about presenting a financial tool; it’s about being part of a solution that feels genuinely supportive. The gap created by reduced efficacy in current strategies indicates that there might be missed opportunities for innovative services that prioritize education and lasting value over quick fixes.
What this means for you, whether a consumer or a provider, is clear: success in the coming years will depend not only on the tools offered but also on how well they align with the nuanced realities of managing modern financial stressors.


