Side A · Liner notes
Evaluating the Financial Impact of an $80K Swimming Pool Investment for Family Engagement
Banking · Words by Maurie Backman · Released
A couple debates spending $80,000 on a pool, weighing its financial feasibility with their retirement funds against the benefits of family bonding.
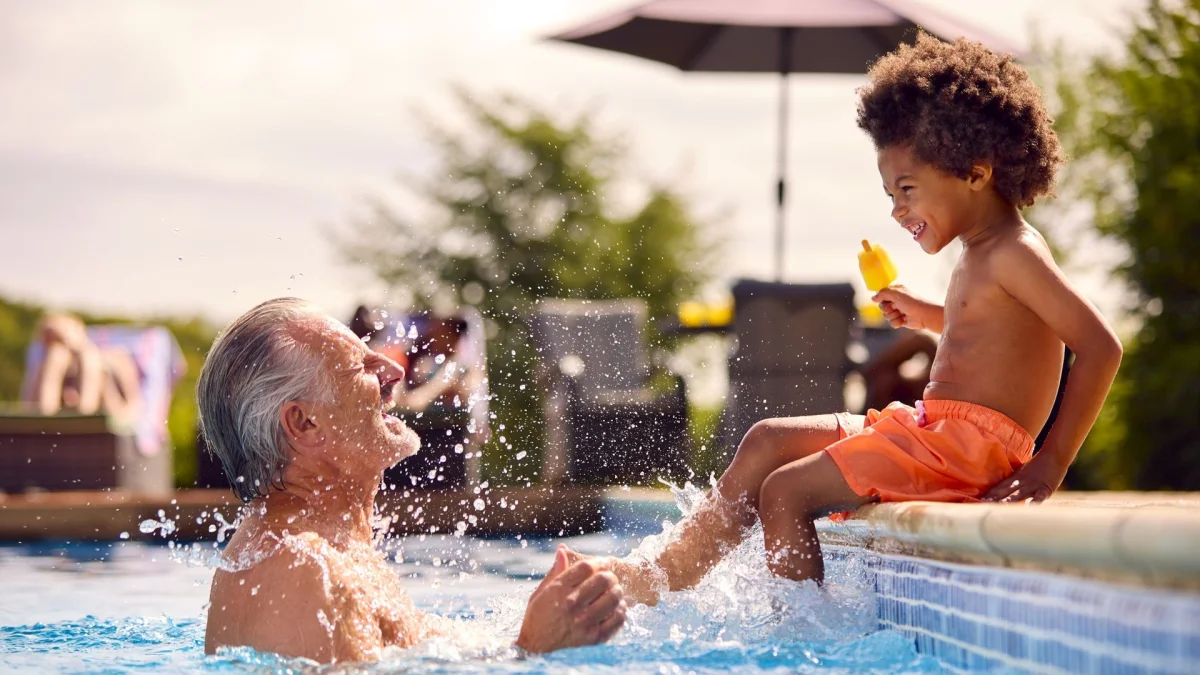
A couple retired last year at 65 with $1.1 million in savings. Their $6,000 monthly Social Security income covers most expenses, but one partner is considering an $80,000 investment in a pool to enhance visits from their grandchildren, while the other believes it is an unnecessary expenditure. This scenario raises essential questions about the financial implications and emotional motivations behind such spending.
Analyzing the Financial Implications
To decide whether this pool investment is wise, we must first assess its impact on their overall financial health. Spending an entire retirement nest egg on a luxury item like a pool is typically frowned upon, but if it's a small fraction of their portfolio, it may be justifiable.
Financial planner Derilyn Freeman suggests the relevant question is whether the couple can afford to purchase the $80,000 pool without jeopardizing their retirement plans. Given their low withdrawal rate from their retirement savings, which is primarily sustained through Social Security, their remaining investment balance becomes central to this analysis.
Assuming they choose to withdraw $80,000 for the pool, their new balance would be $1,020,000. If they later incur $1,500 monthly in maintenance costs—totalling $18,000 annually—this represents an annual withdrawal of about 2% from their savings. Freeman notes that with current rates for high-yield savings accounts and CDs exceeding 3%, it's possible for their overall investment to continue growing even after these withdrawals, assuming inflation and taxes don’t outweigh these gains.
This scenario indicates that purchasing a pool might not negatively impact their retirement savings if managed correctly. Moreover, the average annual cost of pool ownership, according to marketplace Swimply, typically falls between $3,000 and $6,000, suggesting that Freeman's maintenance cost estimates may lean toward the upper end, possibly due to expectations for high-end pool features.
The Psychological Dimensions of Spending
Even if the financial math adds up, emotional factors cannot be overlooked. Many retirees struggle with spending their savings, often feeling guilt about expenditures that don't seem to directly improve their financial situation. Freeman points out that feelings of fear or guilt may underpin the husband's objections to the pool purchase.
It’s essential to gauge not only whether the couple can afford the pool but also whether both partners genuinely want it. If the husband shows less enthusiasm for a pool, alternatives that are less expensive yet still promote family engagement could be explored. A cost-effective above-ground pool or even an outdoor hot tub could suffice in catering to the grandchildren’s enjoyment.
Exploring Other Family-Bonding Alternatives
Once the financial capacity to purchase a pool is determined, it’s also worth considering if it's the most effective way to spend their "fun bucket" savings. Freeman encourages evaluating whether a swimming pool aligns with their broader values and family bonding priorities.
Should the couple find pool maintenance daunting or complicated, redirecting funds toward family vacations, cruises, or experiences in upscale environments such as national parks can provide meaningful quality time without the long-term commitments associated with pool ownership.
The idea is to balance enjoyment and practicality. While a pool can facilitate wonderful family memories, it's crucial to consider if there are more manageable forms of entertainment that would fulfill the same purpose.
Assessing the Long-term Value of a Pool
From a long-term perspective, the decision to invest in a pool should also factor in its resale value. According to Chartered Financial Consultant Steve Azoury, while a pool can enhance a home's value in favorable markets, it can have the opposite effect in regions with shorter swimming seasons or saturated markets. Such environments might render a pool a liability when selling the property, rather than an asset.
Geographic considerations are critical here. If the couple resides in an area conducive to year-round swimming, the pool may result in a sound investment. Conversely, in climates with limited swimming months, the practicality of pool ownership comes into question, particularly regarding its utility during colder seasons and the activities available for grandchildren throughout the year.
Conclusion: Making the Decision
Ultimately, whether to proceed with the pool purchase should hinge on the couple's shared desires and objectives for their retirement lifestyle. If they conclude that fostering a family-oriented gathering place is worth the financial outlay and maintenance challenges, they should feel confident in their choice. After years of hard work, they’ve earned the right to invest in their family's enjoyment.
In sum, careful consideration of both the financial implications and the emotional significance of the purchase will guide the couple in making a decision that best serves their familial aspirations.


