Side A · Liner notes
Economic Insights from the New York Fed's December 2025 DSGE Model Forecast
Banking · Words by Robert Jones · Released
The December 2025 DSGE model forecast from the New York Fed reveals stronger growth projections, rising inflation rates, and adjustments in interest rate predictions compared to prior estimates.
The Federal Reserve Bank of New York's dynamic stochastic general equilibrium (DSGE) model has been updated to reflect economic forecasts for December 2025. The latest insights indicate that growth projections for 2025 have improved due to a more favorable monetary policy outlook and increased productivity. However, inflation expectations have also risen, primarily influenced by cost-push factors, emphasizing the complex economic situation ahead.
Forecast Adjustments Since September 2025
Compared to the September 2025 forecast, anticipated GDP growth for 2025 rose from 1.4 percent to 1.8 percent. This upward revision can be attributed to surprisingly positive economic activity; specifically, GDP growth in Q3 2025 outperformed prior estimates. Such a strong performance in the third quarter is a critical indicator of the underlying economic momentum, suggesting that consumer and business confidence may be stabilizing. The current projection reflects adjustments in anticipated policy rates due to shifts in the Survey of Market Expectations (SME) between July and October 2025, and an unanticipated increase in productivity levels. It’s a signal that the economy may be responding positively to recent monetary policies.
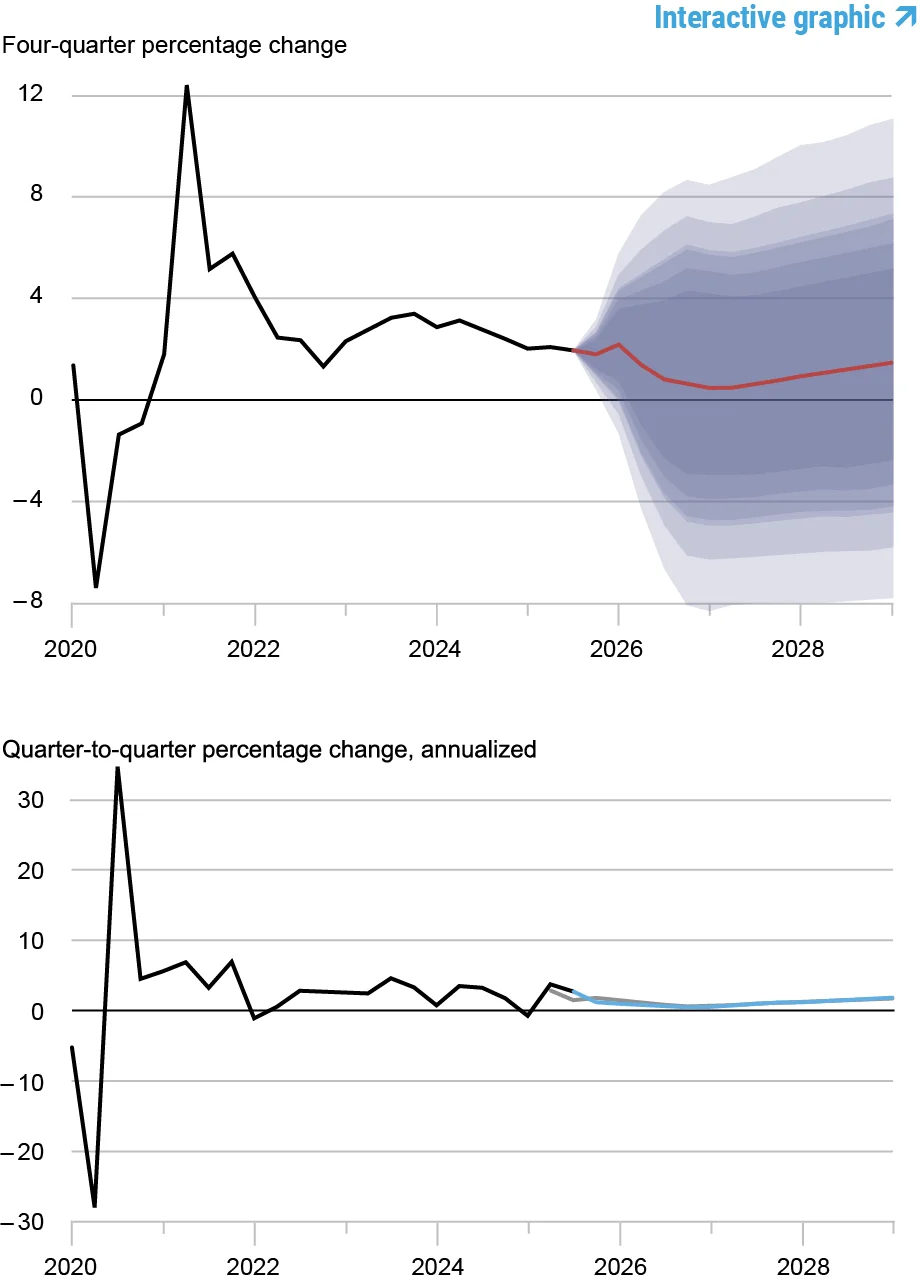
For future years, GDP growth predictions have also been adjusted slightly: 2026 GDP growth is expected at 0.6 percent, down from the previous 0.9 percent estimate, while 2027 and 2028 remain unchanged at 0.8 percent and 1.3 percent, respectively. This reflects a tempered outlook for the mid-term, which could be influenced by a potential tightening of monetary policy as inflationary pressures mount. Noteworthy is that the probability of a recession occurring over the next four quarters, defined as output growth dipping below -1.0 percent, holds steady at 37.5 percent, closely aligning with September's 33 percent forecast. It begs the question: are we seeing a bullish revival, or are the clouds of recession still lurking just in the background?
Inflation Trends and Projections
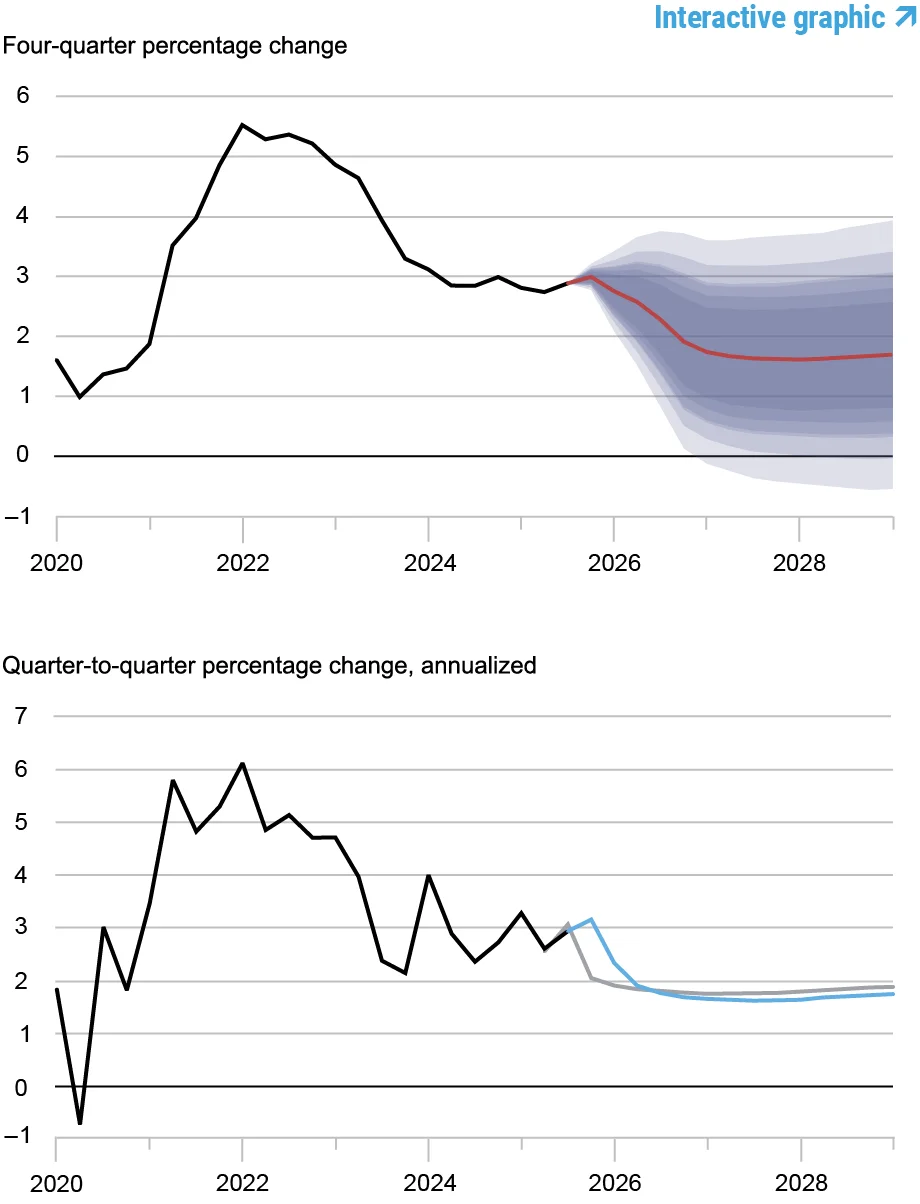
Turning to inflation, core PCE inflation forecasts for Q4 2025 have been upgraded from 2.8 percent in the September model to 3.0 percent. This adjustment reflects input from the Survey of Professional Forecasters (SPF), which suggests heightened inflation pressures primarily driven by cost-push shocks, thought to be influenced by tariffs. Tariffs have become a significant point of contention in economic policy, with their potential to disrupt supply chains and inflate costs passed down to consumers. The inflation outlook for 2026 is similarly raised, now projected at 1.9 percent compared to the prior estimate of 1.8 percent. This is more significant than it looks; persistent inflation can lead to eroded purchasing power and complicate economic recovery efforts.
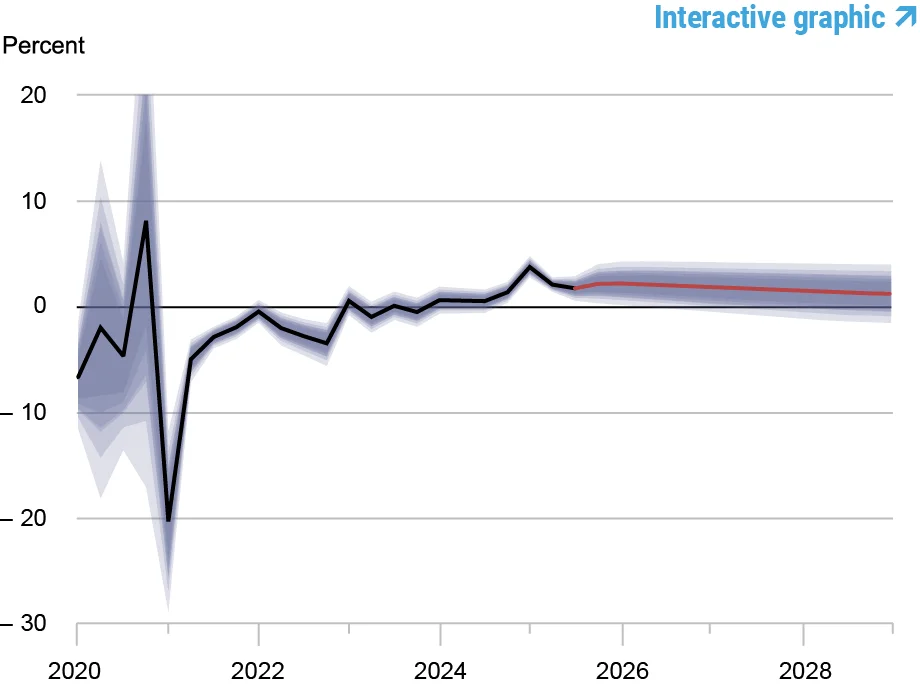
However, the forecast points to a slight reduction in inflation expectations for subsequent years. For 2027, the inflation forecast has decreased from 1.7 percent to 1.6 percent, and for 2028, it adjusts from 1.8 percent to 1.7 percent, indicating a potential easing of inflationary pressures further down the line. This could be interpreted as a sign that while near-term pressures are mounting, there's hope that the economy may stabilize and inflation might become less of a concern in the longer term. But, as this is where most forecasts can go awry, especially if external shocks emerge.

Real Natural Rate of Interest
The real natural rate of interest (r*) predictions for 2025 have been revised downward from 2.6 percent in September to 2.2 percent. This reduction aligns with the observed increase in total factor productivity, which is perceived as largely transitory. Such a drop in the anticipated rate may reflect a reassessment of economic conditions and a recognition that growth may be more modest than previously thought. Predictions for r* remain stable for the latter years of the forecast, with figures of 2.0 percent for 2026, 1.6 percent for 2027, and 1.3 percent for 2028, mirroring earlier estimates for 2027 and 2028. Stability in these rates could be taken as a signal that while the Fed may opt for caution, potential changes in economic performance could still catch policymakers off guard.
This decrease in both the real natural rate of interest and the anticipated policy rate supports a broadly similar stance in monetary policy compared to earlier forecasts, suggesting that adjustments in rates are being taken into account without significantly altering the designed economic framework. If you're working in this space, the interplay between these interest rates and inflation will be crucial in determining the broader economic implications, especially as businesses plan for investment and growth.

Comparative Forecast Data
| Forecast Period | 2025 | 2026 | 2027 | 2028 | ||||
|---|---|---|---|---|---|---|---|---|
| Date of Forecast | Dec 25 | Sep 25 | Dec 25 | Sep 25 | Dec 25 | Sep 25 | Dec 25 | Sep 25 |
| GDP growth (Q4/Q4) | 1.8 (0.9, 2.6) | 1.4 (-0.4, 3.3) | 0.6 (-4.6, 5.9) | 0.9 (-4.5, 6.4) | 0.8 (-4.5, 6.0) | 0.8 (-4.7, 6.2) | 1.3 (-4.3, 6.8) | 1.3 (-4.3, 6.9) |
| Core PCE inflation (Q4/Q4) | 3.0 (2.9, 3.1) | 2.8 (2.5, 3.1) | 1.9 (0.8, 3.0) | 1.8 (0.7, 2.9) | 1.6 (0.4, 2.8) | 1.7 (0.5, 3.0) | 1.7 (0.4, 3.0) | 1.8 (0.5, 3.1) |
| Real natural rate of interest (Q4) | 2.2 (1.1, 3.3) | 2.6 (1.4, 3.8) | 2.0 (0.6, 3.4) | 2.1 (0.6, 3.5) | 1.6 (0.0, 3.1) | 1.6 (0.1, 3.2) | 1.3 (-0.3, 2.9) | 1.4 (-0.3, 3.0) |
Implications for Stakeholders
The adjustments reflected in these forecasts signal a transition period marked by both opportunity and caution. Businesses need to anticipate fluctuations in costs and potential shifts in consumer behavior influenced by inflation pressures. Investors, especially in sectors sensitive to interest rates and economic growth, should carefully assess how these forecasts might affect their strategies.
Moreover, policymakers will have to navigate a delicate balancing act. They face pressure to support growth amid rising inflation, which could limit their options in terms of monetary policy. If inflation continues to outpace expectations, the Fed might have to reconsider its moderate approach. This dynamic could lead to a harsher monetary environment, which could, in turn, impact employment and consumer spending.

Conclusion: Looking Ahead
The current DSGE model forecast frames a stronger economic outlook for 2025, buoyed by productivity gains and a less aggressive monetary policy stance. However, the inflation forecast exhibits notable increases, pointing to the challenges posed by external cost pressures. Moving forward, stakeholders should closely monitor changes in productivity and geopolitical factors to better understand their implications on inflation and growth trajectories. The essence of navigating these trends will be adaptability and vigilance—two qualities that will determine resilience in an uncertain economic climate.